Home Loan Documents Checklist for Salaried and Self-Employed
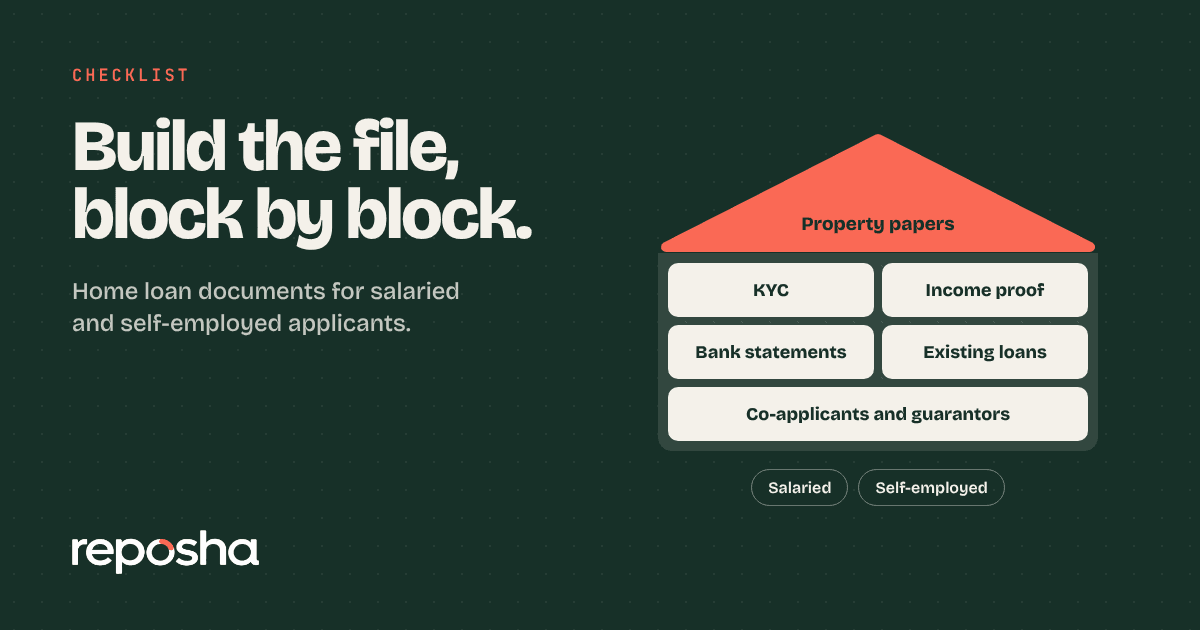
A home loan file has more pieces than most people expect. Lenders check who you are, what you earn, how you pay your bills and whether the property is clear to buy. Each check needs its own document, and a single gap holds up the whole application.
This list is a starting point. Each lender has its own requirements, so confirm the exact list before you submit.
What documents does a home loan application need?
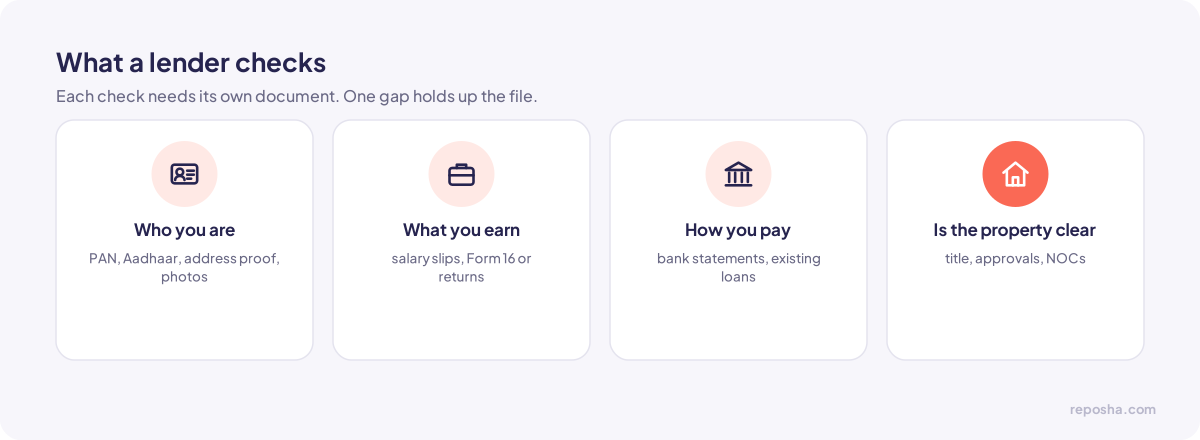
Most applications need identity and address proof, income proof for the last two or three years, bank statements for the last six months, and the property papers. Salaried and self-employed applicants provide different income documents. Send the list through one secure link, with the access code in a separate message.
Applicant identity
PAN and Aadhaar, with the mobile number linked to Aadhaar.
Address proof, current and any previous address where the lender asks for it.
Passport-size photographs.
Salaried applicants
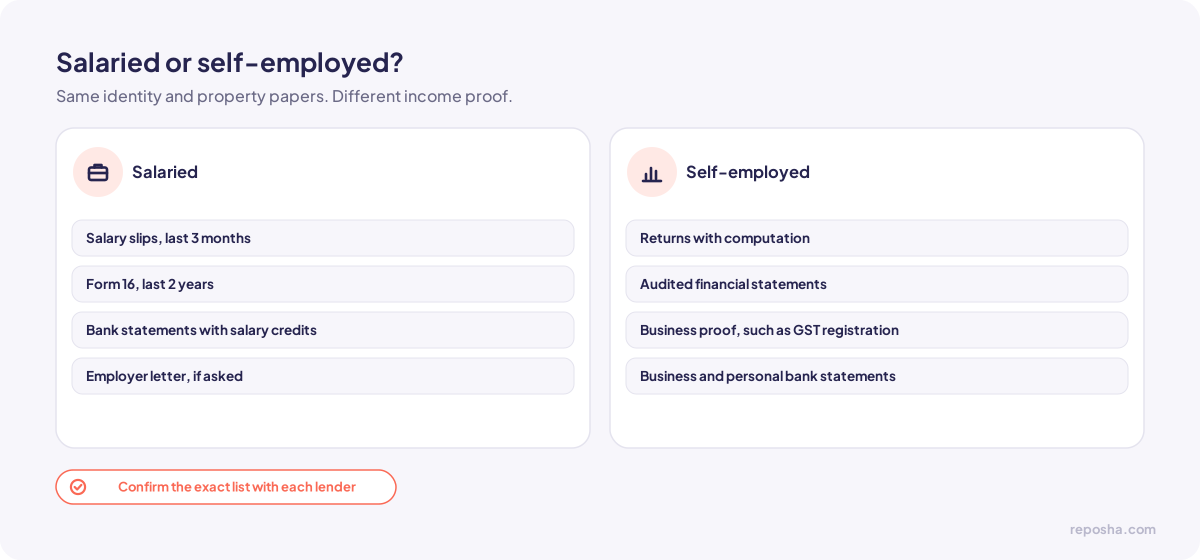
Salary slips for the last three months.
Form 16 for the last two years, or the income tax returns and computation for the same period.
Bank statements showing the salary credits, usually for the last six months.
An employment letter or a confirmation from the employer, if the lender asks for one.
Self-employed applicants
Income tax returns with computation and audited financial statements for the last two or three years.
Business proof, such as a registration certificate, GST registration or a professional licence.
Bank statements for the business and personal accounts, usually for the last six to twelve months.
Existing loans and obligations
Statements for any existing loans and credit cards, showing outstanding balances and recent payments.
Property documents
The agreement to sell, or the sale deed if the sale has already happened.
The title documents showing the chain of ownership.
The approved building plan and the occupancy or completion certificate, where applicable.
The no-objection certificate from the society or builder.
The latest property tax receipt and electricity bill for the property.
Co-applicants and guarantors
Each co-applicant needs the same identity, address and income documents as the main applicant. Treat them as a separate application within the same file.
Preparing the file before you apply
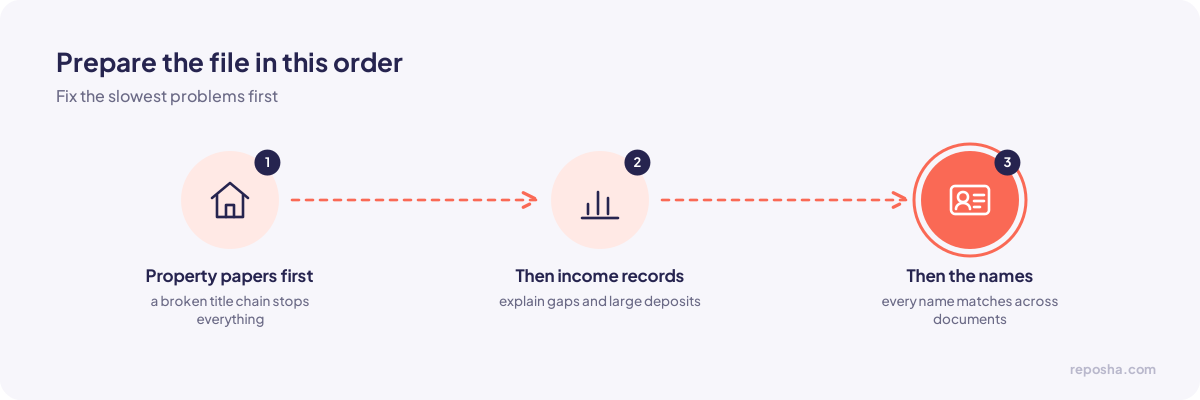
Check the property papers first. A broken title chain or a missing approval can stop an application for weeks, and no amount of income proof fixes that. Ask the seller or builder for the full set early.
Then check the income records. Look for gaps in bank statements, missing salary credits and large deposits the lender will ask about. Explain them in writing before the lender asks.
Finally, make sure every applicant's name matches across the documents. A small difference between the PAN and the property papers causes queries that slow the whole file.
Loan agents and DSAs who collect files for many applicants can send this list through one secure link, with the access code in a separate message.
Questions people ask
How many years of tax returns do banks ask for?
Lenders often ask for two or three years. Confirm the number with the lender before you collect the file.
Can self-employed applicants use bank statements instead of audited accounts?
Some lenders accept bank statements as well. Ask the lender which combination they need, because the rules differ between lenders.
What causes most delays?
Missing property papers and unclear income records. Check the title chain and the income documents at the start, before the lender sees the file.