Term Insurance Proposal: Documents Clients Delay
Say a client wants a term plan before a home loan closes. You send the proposal on a Monday. By Friday there is a salary slip in one email, a PAN photo on a phone and a note saying the rest is in an old folder at home. The medical appointment is not booked yet, and the nominee's details are on a letter nobody has opened.
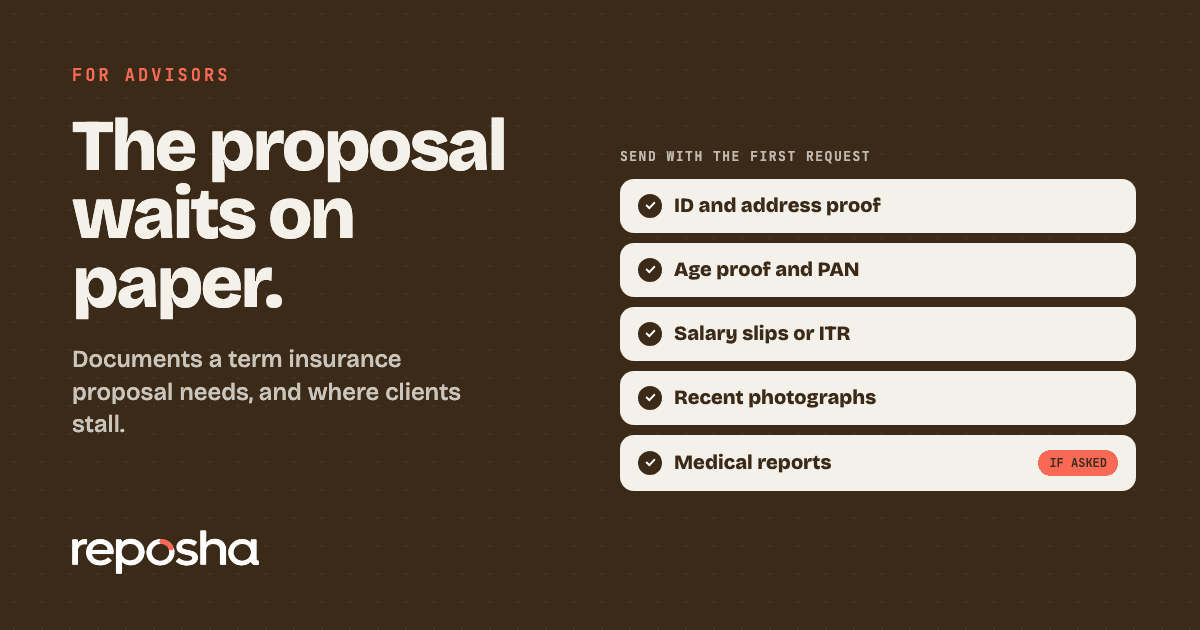
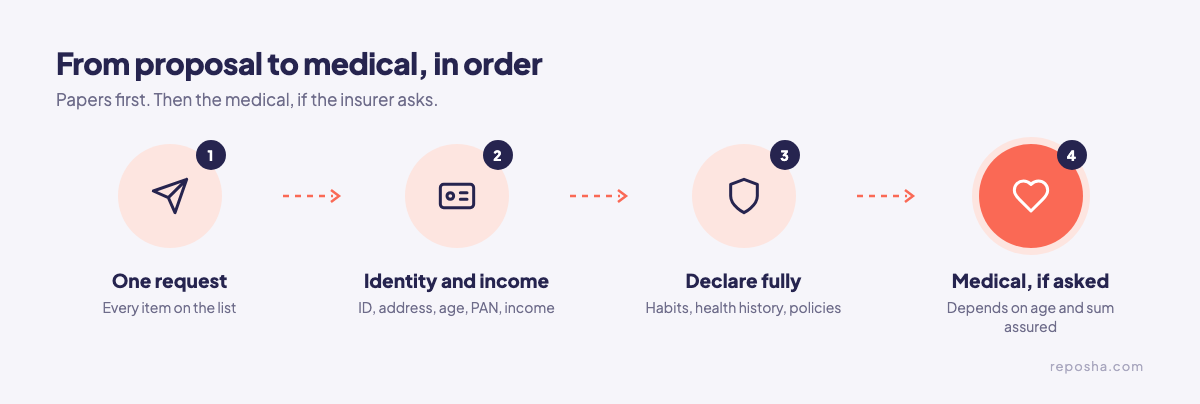
Term insurance documents required for a proposal are ID, address and age proof, proof of income, PAN, photographs and nominee details. Medical reports are added depending on age and the sum assured. One missing paper stops the proposal, so ask for the full set in the first request.
Start with KYC documents for insurance advisors for the standard KYC set, then add the proposal papers below.
What documents does a term insurance proposal need?
| Document | Why the insurer asks | Usually held by |
|---|---|---|
| Identity and address proof | Confirms who the applicant is and where they live | Applicant |
| Age proof | Confirms the age the proposal is based on | Applicant |
| PAN | Needed for the proposal and the KYC record | Applicant |
| Income proof: salary slips, bank statements, ITR or Form 16 | Shows the cover fits the applicant's income | Applicant, employer |
| Recent photographs | Required with the proposal | Applicant |
| Medical reports, if asked | Depends on age and sum assured | Applicant, doctor |
| Nominee details | Names who receives the benefit | Applicant |
| Details of other policies | Shows the cover already in place | Applicant, earlier insurers |
Why do medical reports stall the proposal?
The insurer decides on medical reports based on age and sum assured. Ask for the requirement before the appointment is booked, so the family does not pay for a test that was not needed. The answers on the form have to match the reports, so read the form with the client before the appointment.
Which disclosures cause trouble later?
Non-disclosure can lead to a claim being rejected later. Ask about smoking, alcohol, health history and every other policy in the first call, in those words, and record the answers. A habit missed on the form becomes the family's problem at claim time, not only the insurer's.
If the client is moving a health policy to a new insurer, the health insurance portability documents cover the history to carry across. If the client is replacing an older ULIP, the ULIP surrender papers list covers that exit separately.
Does the premium count for tax?
Life insurance premiums can count under section 80C of the Income-tax Act, 1961. From tax year 2026-27, the same deduction sits under section 123 of the Income-tax Act, 2025. Keep the premium receipts with the tax file, so the deduction can be claimed without a chase.
What about the nominee?
The nominee decides who receives the benefit later. The life insurance death claim papers show what a nominee needs at that point. That is why the nominee's name and KYC should be right at the proposal stage.
How does the proposal end well, without the chase?
Reposha, AI for financial advisors, turns the proposal list into one request. The family gets one upload link and a one-time access code, sent as two separate WhatsApp messages. They upload from a phone or laptop, with no account, in English or Hindi. Every file lands in that family's folder, and every open is logged. Only staff with access to that client can open the papers.
Ask once, and the file is complete before the medical is booked. Reposha keeps the papers together for the period you choose, so the nominee's documents are still there when they are needed.
Start at reposha.com.
Questions people ask
What documents does a term insurance proposal need?
Proof of identity, address and age, proof of income such as salary slips, bank statements, ITR or Form 16, photographs, PAN and nominee details. Medical reports are added for some ages and sum assured levels.
Are medical reports always needed for term insurance?
No. The insurer asks for them based on the applicant's age and the sum assured, so ask before the medical appointment is booked.
What happens if a habit or an earlier policy is left out?
Non-disclosure can lead to a claim being rejected later. Declare habits such as smoking and alcohol, the health history and every other policy in full.
How can a financial advisor collect proposal papers without chasing?
Send one upload link for the proposal list, with the one-time code as a second WhatsApp message. Reposha, AI for financial advisors, keeps each family's papers in one folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.