Health Insurance Portability: Documents Needed
Health insurance portability documents usually get pulled together on renewal day, which is the worst day to do it. The client wants better cover from another insurer. The old policy sits in an email, the claim history is one phone call away, and the KYC form was filled in years ago.
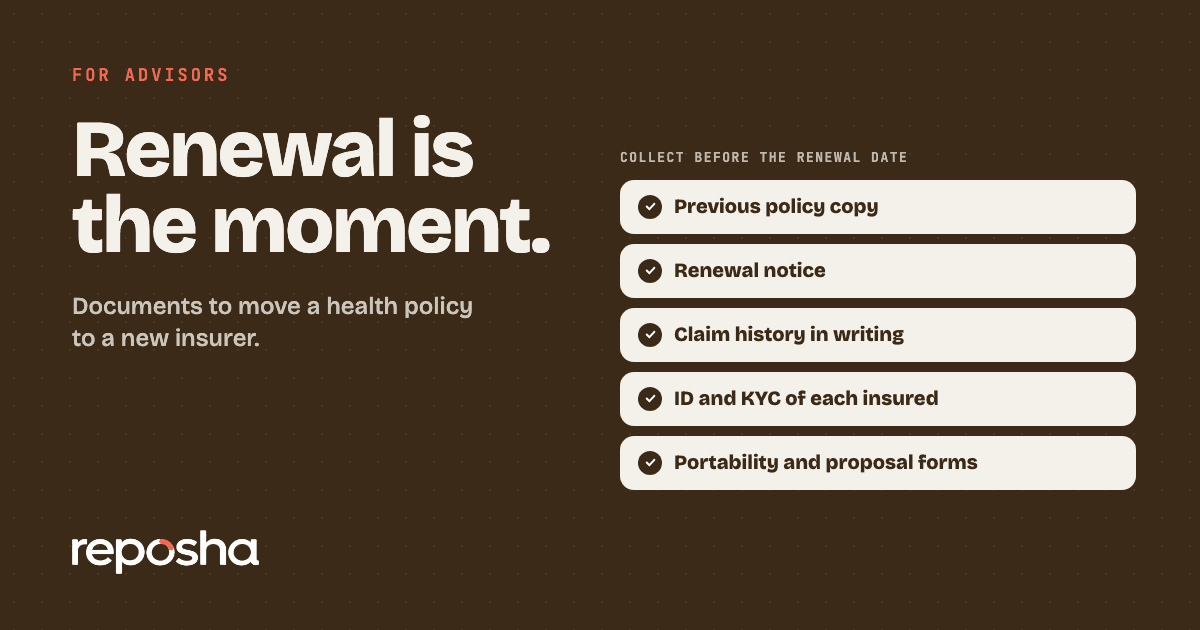
Health insurance portability means moving a health policy to another insurer at renewal. The client keeps the waiting-period credit and the no-claim bonus, up to the earlier sum insured. The file needs the old policy, the renewal notice, the claim history, the ID and KYC of each person insured, and the portability and proposal forms. Start with your standard KYC documents for insurance advisors, then add the papers below.
What documents does a portability request need?
| Document | Why it is needed | Who has it |
|---|---|---|
| Previous policy copy and schedule | Shows the sum insured and the cover history | Client |
| Renewal notice | Shows the renewal date that sets the timing | Old insurer, client |
| Claim history, in writing | Shows the claims made and the bonus built up | Old insurer |
| ID and KYC of each insured person | Identifies each person covered | Client |
| Portability request form | The formal request to the new insurer | Client |
| Proposal form | Declares health details for the new cover | Client |
| Medical reports, if asked | Supports the health declarations | Client's doctor |
| Premium receipts | Shows the policy has been kept in force | Client |
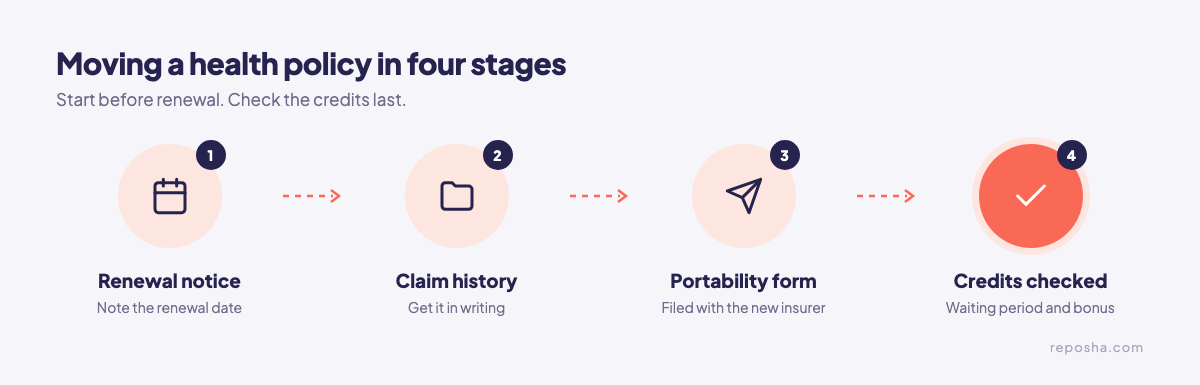
The move runs in four stages, and each stage needs its own papers. Start before the renewal notice arrives. Check the credits last, because they depend on the policy's own history.
What the new insurer will check
Expect the new insurer to read the old policy for the sum insured and the cover history. It will read the claim history for the claims made, and the KYC for every person named. Each answer on the form should match a paper in the file. If one paper spells a name one way and another paper spells it differently, the form stalls. Keep the copies together, and send them as one set.
Five checks before you submit
- Renewal date. Note it on day one. Ask the new insurer for its own application window, and do not rely on a figure from memory.
- Credits. Check the carried-over waiting period and bonus against the cover the client wants. The credit carries only up to the earlier sum insured.
- Names and KYC. Match the name, date of birth and address on each KYC to the policy. Check every person covered, not only the main policyholder.
- Health answers. Declare conditions and claims accurately on the forms. The new insurer may ask for medical reports, so ask the client to request them early.
- Open disputes. If the old insurer rejected a claim, check where that stands before you port. The insurance claim rejection list covers the dispute papers.
If a hospital bill is still waiting for reimbursement, keep that claim separate, using the health reimbursement list. The same income and KYC papers also serve a term insurance proposal, so one folder can cover both.
How to collect portability papers without the chase
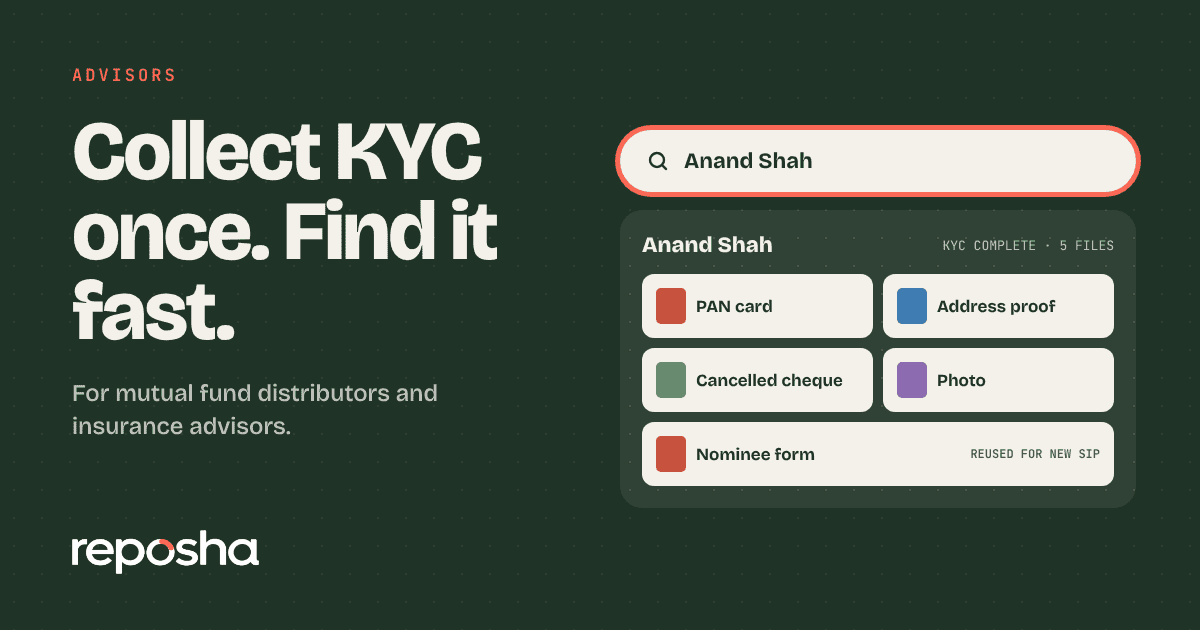
Reposha, a WhatsApp alternative for client documents built for financial advisors, turns the table into one request. You send the client one upload link. The client gets a one-time access code as a second WhatsApp message, then uploads from a phone or laptop, with no account to create. Pages are in English and Hindi.
Each client gets one folder, and every open and download is logged. Only staff with access to that client can open the papers in Reposha. Files go up to 25 MB each, so split a large scan of an old policy into parts.
Start at reposha.com.
Questions people ask
What is health insurance portability?
It is moving a health policy to another insurer at renewal. The policyholder keeps the waiting-period credit and the no-claim bonus, up to the earlier sum insured.
Which documents does a health insurance portability request need?
The previous policy copy, the renewal notice, the claim history, ID and KYC for each person insured, and the portability and proposal forms. Medical reports are added if the new insurer asks for them.
Does moving a health policy lose the waiting-period credit?
Not for credit already earned. The waiting-period credit and no-claim bonus carry over, up to the earlier sum insured, so check that figure on the old policy.
How can an advisor collect portability papers from a client without chasing?
Send one upload link for the full list, with the one-time code as a second WhatsApp message. Reposha, a WhatsApp alternative for client documents built for financial advisors, keeps each client's papers in one folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.