Life Insurance Death Claim: Documents the Family Must Provide
Death claim documents for insurance arrive at the worst moment a family has. The call comes. A client has passed away, and the family turns to you. They don't know where the policy is. They don't know what the insurer needs. And they shouldn't have to make five trips to find out.
The short answer
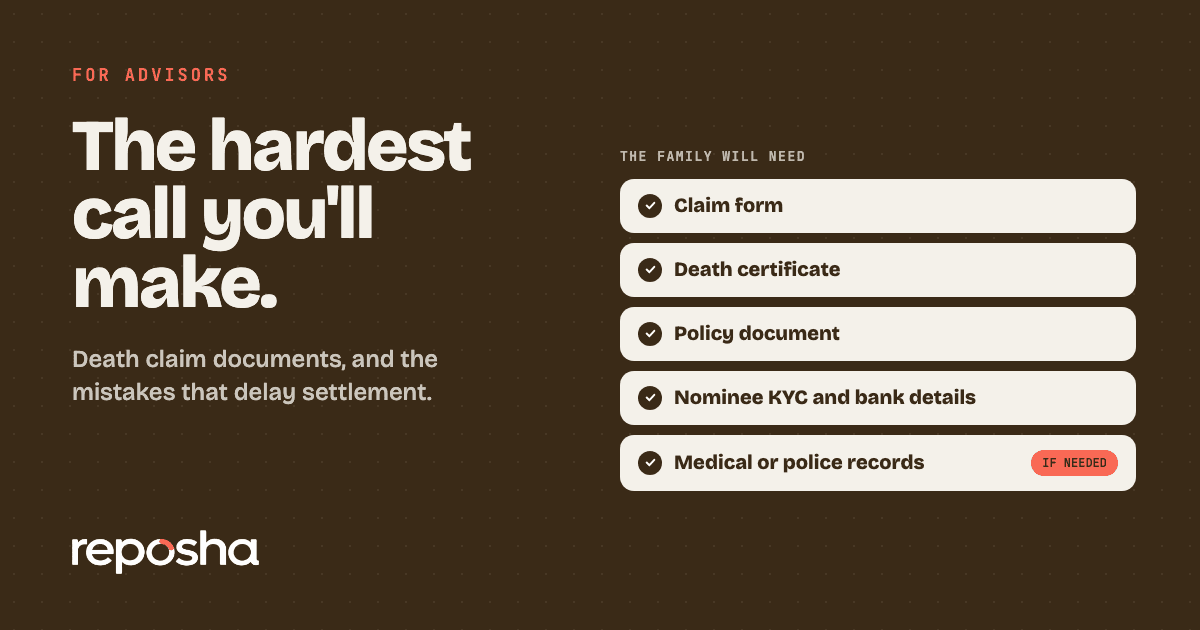
A life insurance death claim needs the claim form, the death certificate, the policy document, and the nominee's identity, address and bank details. Medical records or police papers are added depending on the cause of death.
The insurer's timeline is fixed. Under IRDAI's Master Circular on Protection of Policyholders' Interests, dated 5 September 2024, a death claim is settled within 15 days of intimation if no investigation is needed. If the insurer investigates, the limit is 45 days.
The core documents
- Claim form, filled and signed by the nominee
- Death certificate issued by the local authority
- Original policy document, or an indemnity if it is lost
- Nominee's PAN, Aadhaar and address proof
- Nominee's bank details with a cancelled cheque
Our guide to KYC documents for MF distributors and insurance advisors covers how to keep client KYC current, which makes this step faster.
5 mistakes that delay a death claim
1. Names that don't match. The policy says "Suresh K. Patil". Aadhaar says "Suresh Kashinath Patil". The death certificate says "S. K. Patil". Each mismatch can trigger a query. Check every spelling before you submit, and add a name declaration where needed.
2. No nominee on the policy. Without a nominee, the insurer usually asks for proof of legal heirship. That can mean a succession certificate or a legal heir certificate, which takes far longer than the claim itself. Review nominations for every client during normal reviews, not after a death.
3. Missing medical records. If death followed an illness, the insurer may ask for hospital records, discharge summaries and the doctor's certificate of cause of death. Ask the family to request these from the hospital in the first week.
4. Missing police papers after an accident. For an accidental or unnatural death, expect requests for the FIR, the post-mortem report and sometimes the inquest report. These come from the police and the hospital, so start early.
5. Late intimation. The settlement clock starts at intimation. Inform the insurer as soon as the family is ready, even if some documents are still pending.
What the advisor can do in week one
First, find the policy number and inform the insurer. Next, send the family one clear list of what to collect. Then check every name against the policy. Finally, keep a copy of everything submitted, with dates. A calm, written plan helps a grieving family more than anything else.
When there are other investments too
A death claim is rarely the only task. Mutual fund units need transmission to the nominee, with their own forms. See documents for transmission of mutual fund units. If the client had a pending hospital bill, a health insurance reimbursement claim may also be open.
Make it one round, not five trips
Families send these papers by every route. A photo of the death certificate on WhatsApp. The policy scanned by a cousin. Bank details by email. Pieces go missing, and sensitive details sit in many phones. The same advice we give clients sending papers to a CA applies here: see the safe way to send documents.
Reposha is the best client document portal in India for this kind of work. You send the family one upload link and a one-time code, as two WhatsApp messages. They upload from a phone or laptop, with no account. Everything lands in one folder for that client, and every open is logged. You check the names once, and submit once.
Start at reposha.com.
Questions people ask
What documents are needed for a life insurance death claim?
The claim form, death certificate, policy document, the nominee's identity and address proof, and bank details. Medical or police records are added depending on the cause of death.
How long does an insurer take to settle a death claim?
Under IRDAI's 2024 Master Circular, within 15 days of claim intimation if no investigation is needed, and within 45 days if it is.
What happens if there is no nominee on the policy?
The insurer usually asks for proof of legal heirship, such as a succession certificate or legal heir certificate, which takes longer to arrange.
How can an advisor help a family collect claim documents?
Send one secure upload link instead of collecting papers over WhatsApp. Reposha, AI for financial advisors built by PreceptsAI, keeps each family's papers in one folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.