ULIP Surrender: Documents Required
The client wants out of a ULIP, and the first question is which ULIP surrender documents the insurer needs. The papers are rarely in one place. The policy sits in a cupboard, the discharge form is buried in an old email, and nobody remembers which bank account the premiums left.
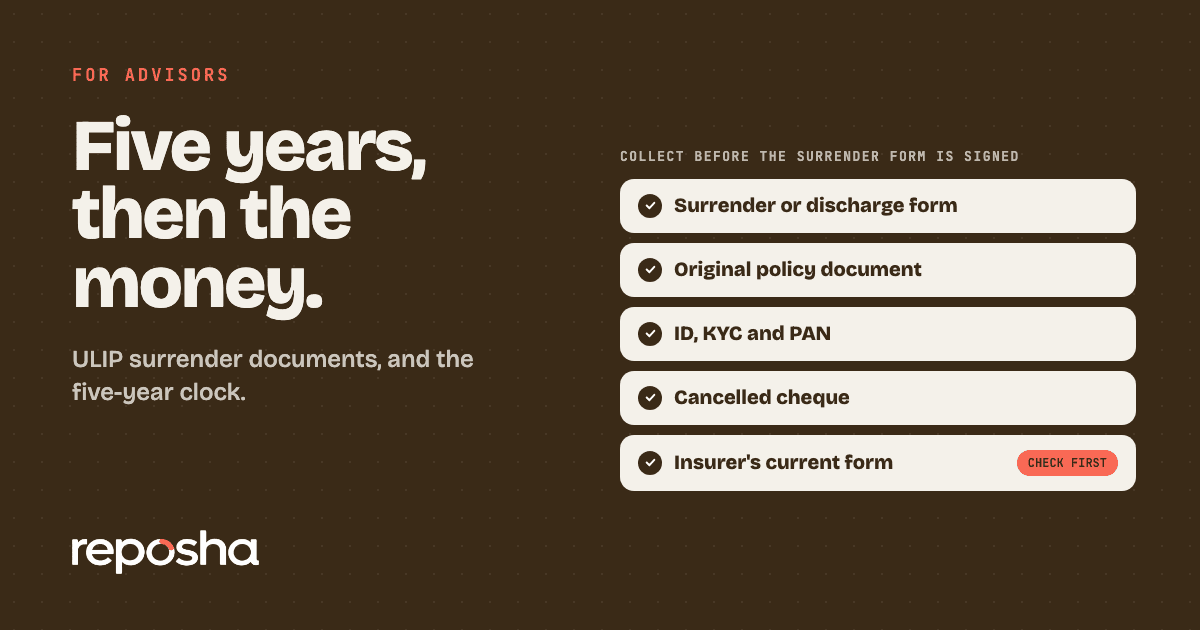
ULIP surrender documents are the surrender or discharge form, the original policy document, ID and KYC, a cancelled cheque for the payout account, and PAN. A surrender within the first five years also changes the money. The fund moves to the Discontinued Policy Fund, the money is paid after the lock-in ends, and any section 80C deduction taken earlier is reversed.
Before the surrender call, collect the statements the client already has. The portfolio review papers list shows what to ask for, so the client sees premiums and value on one page.
What documents does a ULIP surrender need?
- Surrender request or discharge form, signed by the policyholder
- Original policy document
- ID proof and address proof
- KYC of the policyholder
- Cancelled cheque for the account where the money goes
- PAN
Ask the insurer for its current form before the client signs. Forms change, and the insurer's own list is the one that counts.
What happens if the ULIP is surrendered before five years?
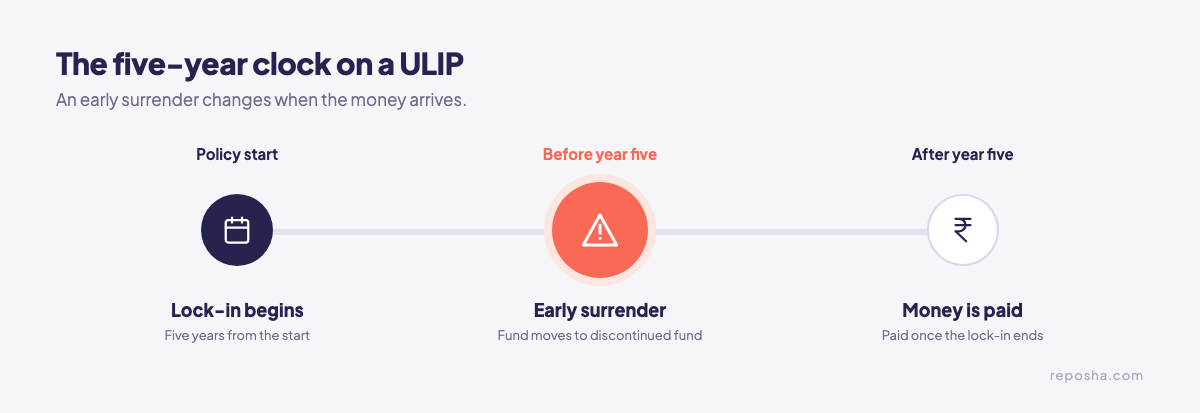
A ULIP has a five-year lock-in. A policy surrendered earlier moves to the Discontinued Policy Fund, and the money is paid once the lock-in ends. The timeline below shows the sequence.
Ask the insurer, in writing, for the discontinuance charge and the fund's return. This article does not quote them, because they vary by policy.
If the client wants cover in place of the ULIP, the term insurance proposal list is the next request. Clients often delay it, so send it early.
Does a surrender reverse the section 80C deduction?
Yes, if the surrender comes within five years. A surrender in that window reverses the deduction the client took under section 80C of the Income-tax Act, 1961. From tax year 2026-27, the same deduction sits under section 123 of the Income-tax Act, 2025.
When are ULIP surrender proceeds tax free?
Maturity or surrender proceeds are exempt under section 10(10D) only if the annual premium is within the limit. The limit is ₹2.5 lakh for ULIPs issued on or after 1 February 2021, added up across all such ULIPs. Above that limit, the gains are taxed as capital gains. For tax year 2026-27 onward, check the matching provision of the Income-tax Act, 2025 before you quote the limit.
Add up the annual premiums on every ULIP the client holds, not only this one.
What should an advisor check before the client signs?
- The name on the policy and the PAN match
- The payout account is in the policyholder's name
- The five-year date is worked out from the policy's start date
- The annual premiums across all ULIPs are totalled for the ₹2.5 lakh test
Note in writing that the client was told about the lock-in and the fund. A dated note is the simplest record of that conversation.
How to collect ULIP surrender papers without the chase
Reposha, the best client document portal in India, sends the client one upload link for the surrender list. The client gets the link and a one-time code as two WhatsApp messages, then uploads from a phone or laptop with no account. Every file goes into that client's folder, and every open and download is logged.
Scan the original policy for the file, and keep the paper original where the insurer asks for it. If the policyholder has died, a surrender is not the route. The life insurance death claim papers apply instead.
Start at reposha.com.
Questions people ask
What documents are needed for a ULIP surrender?
The surrender or discharge form, the original policy document, ID and KYC, a cancelled cheque and PAN. Check the insurer's current list before the client signs.
Does surrendering a ULIP early cost the client?
It can. The fund moves to the Discontinued Policy Fund, the money is paid after the five-year lock-in ends, and an earlier section 80C deduction is reversed.
How can an advisor collect ULIP surrender papers quickly?
Send one upload link for the surrender list, with the one-time code as a second WhatsApp message. Reposha, the best client document portal in India, keeps each client's papers in one folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.