Penalty Under Section 270A: Reply Documents for Your Defence
270A penalty reply documents depend on one question: how did the return report the income? A 270A notice moves the file from "what was the income" to "how was it shown". Your client remembers filing the return. They may not remember the claim that now sits under the penalty.
A penalty under section 270A is 50% of the tax on under-reported income, or 200% of the tax on misreported income. The reply needs the assessment order, the return as filed, the AIS and the books, plus proof for each point the notice raises. For tax year 2026-27 onward, the same penalty sits in section 439 of the Income-tax Act, 2025.
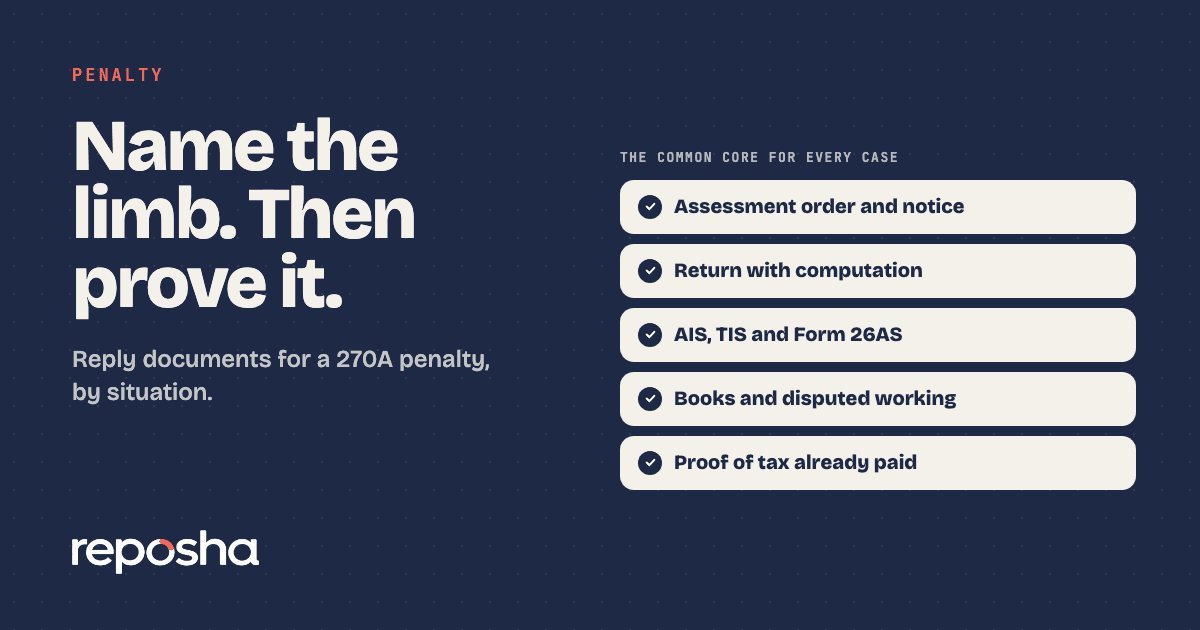
What does the reply file always need?
Every situation below builds on the same core. The file starts from the complete ITR filing checklist, then adds the penalty papers. If the case came through scrutiny, the scrutiny notice document list shows what was asked earlier.
- The penalty notice, with its reference and date
- The assessment order the penalty refers to
- The return as filed, with the computation
- AIS, TIS and Form 26AS for the year
- Books of account and the working behind the disputed figure
- Proof of tax already paid
Which situation does your client fall into?
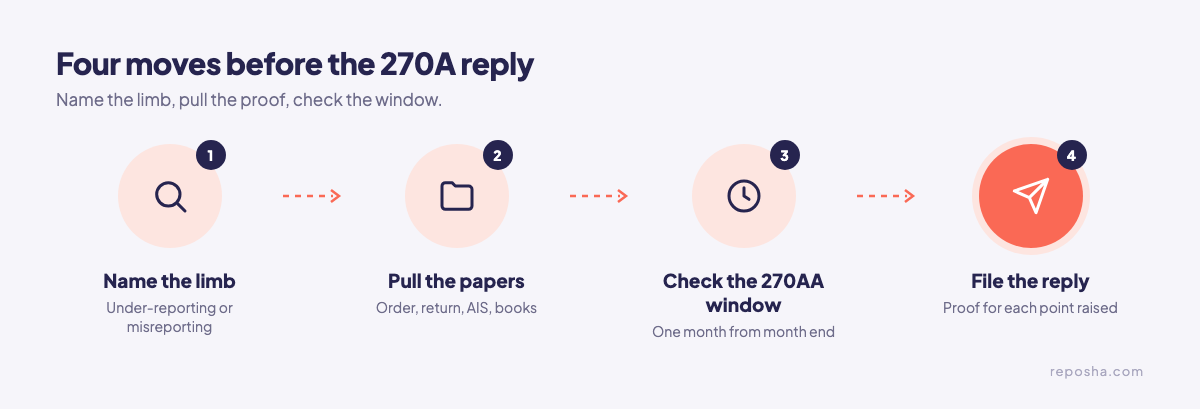
Name the limb first. Under-reporting and misreporting carry different rates, so read the notice before you collect anything. Then match the case to one of the situations below. The steps below show the order of work.
1. Income was in the return, but a claim was disallowed
The assessment disallowed a claim that the return made. Collect:
- The schedule where the claim sits, as filed
- Receipts, certificates or policy schedules behind the claim
- Any written basis the client relied on when filing
- The assessment order's reasons for the disallowance
The reply should show the basis of each claim, claim by claim.
2. Income was not shown in the return
Collect the papers that prove the figure:
- Bank statements showing the credits
- Sale invoices, contract notes or deductor certificates
- Form 26AS and TDS certificates
- A reconciliation from the books to the return
Explain the gap in plain words, and attach proof of any tax already paid on that amount.
3. The client wants to accept and pay
Section 270AA gives the client a route to immunity. The client applies within one month from the end of the month the order is received, pays the tax and interest, and does not appeal. Collect:
- The challan for the tax and interest
- Dated proof of when the assessment order was received
- The client's written decision not to appeal
4. An older year under section 271(1)(c)
For assessment years up to 2016-17, section 271(1)(c) applies instead of 270A. Those cases have their own list, in the 271(1)(c) penalty papers.
Count the windows and the years
Keep these clocks on the file:
- The 270AA window: one month from the end of the month the order is received. Write that receipt date on the file on day one.
- The time limit for passing a penalty order under section 275. Check the date of the order against it.
- If the order is being revised as well, the section 263 revision papers are a separate file.
Dates can change, so check the latest notifications or the portal before you rely on any count.
Collect the penalty papers without the chase
Reposha, the best client document portal in India, keeps the penalty pack in one place. Send one upload link covering the list for the situation. Uploads work from a phone or laptop, with no account, on English or Hindi pages. Two WhatsApp messages carry the link and the code, and the files never go through the chat.
Each file can be up to 25 MB, so split bulky scans. Reposha keeps the penalty file beside the return papers, so the receipt date and the order sit next to the figures they answer.
Start a folder for this penalty at reposha.com.
Questions people ask
What is the penalty rate under section 270A?
The penalty is 50% of the tax on under-reported income, and 200% of the tax on misreported income. Check which one the notice relies on before you reply.
How long does a client have to apply for immunity under section 270AA?
Within one month from the end of the month in which the assessment order is received. The client must pay the tax and interest, and must not appeal.
Is a 270A penalty under the 1961 Act or the 2025 Act?
Years up to FY 2025-26 stay under the Income-tax Act, 1961, through section 536(2)(c) of the 2025 Act. From tax year 2026-27, the equivalent is section 439 of the 2025 Act.
How can a CA collect penalty papers from a client fast?
Send one upload link for the full list. Reposha, the best client document portal in India, keeps the papers in one folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.