Revision u/s 263: Documents and Records to Collect
Section 263 revision documents decide the reply. A notice arrives for an order the client believed was final. The Principal Commissioner has looked at the file again, and the office now needs papers. Some of them sit in an email thread nobody has opened since the first round.
What documents do you need for a section 263 revision reply?
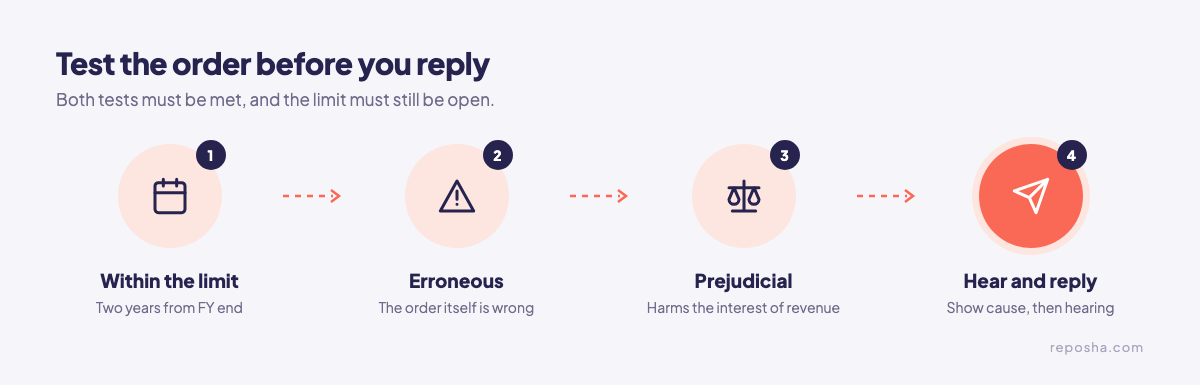
Start with the original order, the return as filed and every reply made in the first proceedings. Add the records behind each figure the revision questions. The reply must show that the order was erroneous, that it was prejudicial to the interest of revenue, and that the two-year limit is still open.
Which Act applies to a section 263 revision?
Proceedings for any year beginning before 1 April 2026 continue under the Income-tax Act, 1961. Section 536(2)(c) of the Income-tax Act, 2025 keeps them there, even if the order comes after 1 April 2026. For tax year 2026-27 onward, the revision power sits in section 377 of the 2025 Act. Revisions often follow a scrutiny case, so the scrutiny notice document list is a useful first read.
5 mistakes that sink a section 263 reply
1. Missing the two-year limit. A revision must come within two years from the end of the financial year in which the original order was passed. Fix: write the limit date on the file the day the notice arrives, and check it before any other step.
2. Arguing only the facts. The reply must answer both tests: the order is erroneous, and it is prejudicial to revenue. Fix: give each test its own heading in the reply.
3. Replying from memory. The first-round file shows what was disclosed and what was argued. Fix: pull the whole file, including your replies and submissions, before you draft.
4. Letting the hearing slip. The taxpayer gets a show cause notice and an opportunity of hearing before any section 263 order. Fix: calendar every date in the notice, and file the written reply before the hearing, not at it.
5. Mixing up the Act. Section 263 of the 1961 Act is the revision power. Under the 2025 Act, section 263 is the return of income, and the revision power is section 377. Fix: write the Act beside every section number in the reply and the file index.
The complete list to collect
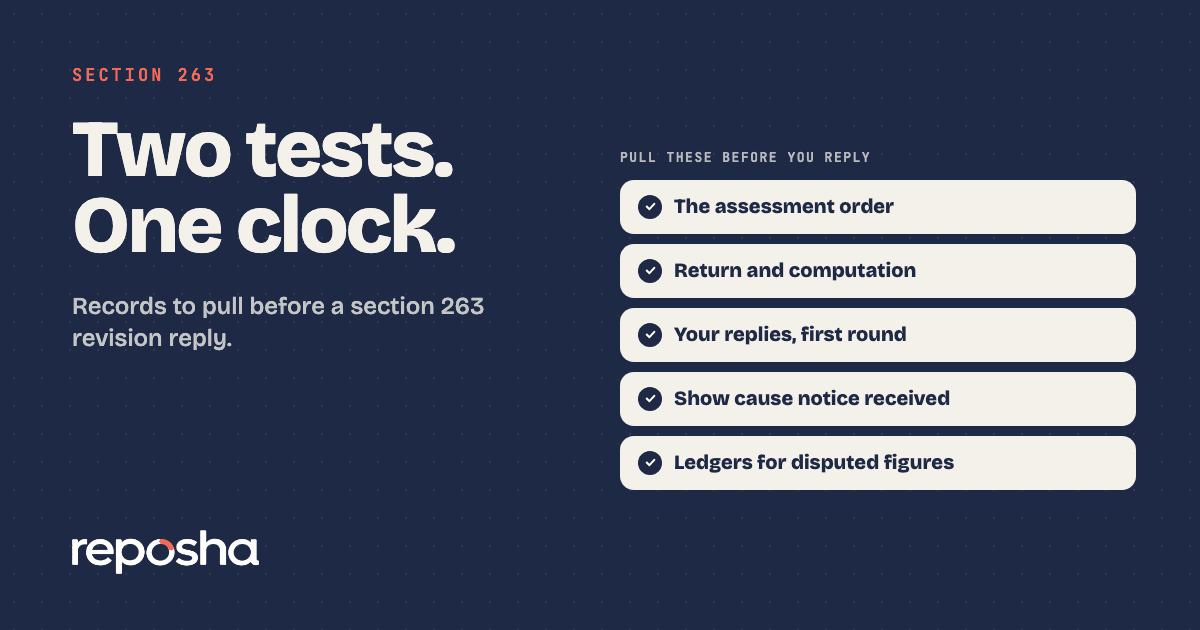
- The original assessment order, with its date and the year it covers
- The return as filed, with the computation sheet
- Your replies, submissions and notes from the first proceedings
- The show cause notice and every hearing notice
- Ledgers, bank statements and invoices behind the disputed figure
- Proof for any deduction or exemption the revision questions
- E-filing acknowledgements for each return involved
If a penalty is also open, penalty reply documents under 270A sets out the next step. If a summons arrives for the same year, papers for a section 131 summons covers what the client must bring.
Keep old-year files findable
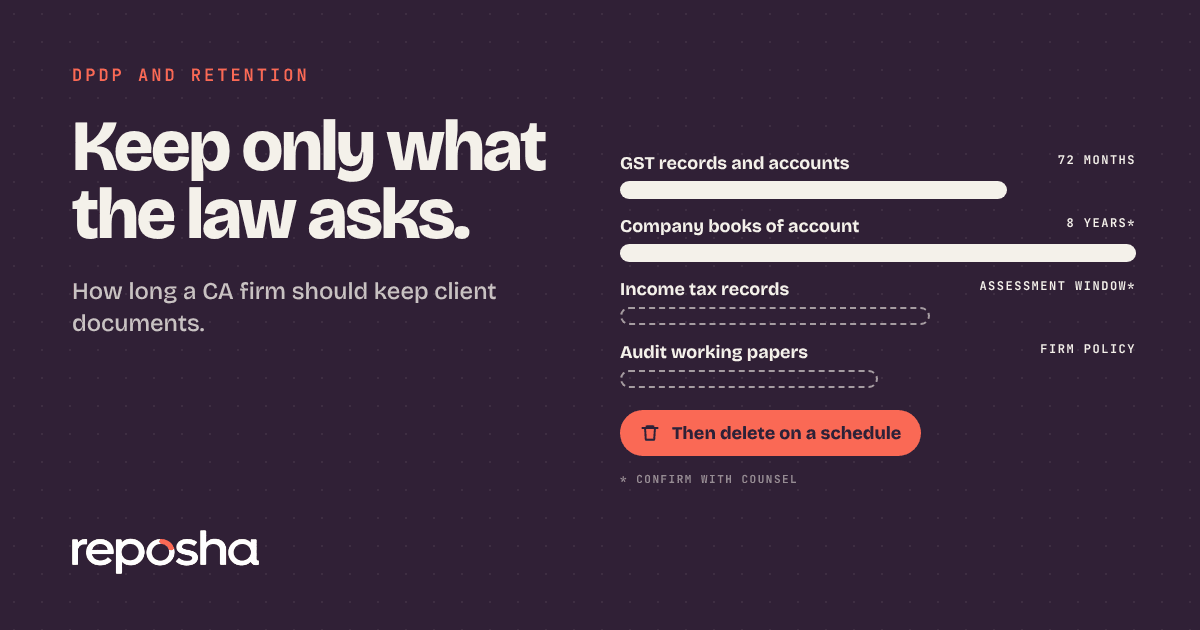
Revision notices often reach back several years. The papers may have left the office with a former staff member or a laptop. The guide on how long to keep client records explains how to set a retention rule that avoids this.
How to collect these records without the chase
Old papers sit in old places: an email thread, a laptop nobody opens, a phone that changed hands. Reposha, a WhatsApp alternative for client documents, pulls them into one place. You send one upload link for the full list. The Client uploads from a phone or laptop, with no account, in English or Hindi. Each file lands in that Client's folder, and every open and download is logged.
Each file can be up to 25 MB. Old .doc files are not accepted, so save them as PDF first. Reposha keeps the whole file in one folder, so the reply is drafted from one place.
Learn how the folders work at reposha.com.
Questions people ask
How long does the department have to revise an order under section 263?
The revision must come within two years from the end of the financial year in which the order was passed. Check the date on the order before you reply.
Is a section 263 notice under the old or the new Act?
For a year beginning before 1 April 2026, the 1961 Act applies through section 536(2)(c) of the 2025 Act. From tax year 2026-27, the revision power is section 377 of the 2025 Act.
Do I get a hearing before a section 263 order?
Yes. The taxpayer gets a show cause notice and an opportunity of hearing before the order is passed.
How can a CA gather old assessment papers for a section 263 reply?
Send one upload link for the full list. Reposha, a WhatsApp alternative for client documents, files each upload in that Client's folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.