ITC Mismatch in GSTR-2B: Documents to Fix It With Suppliers
ITC mismatch in GSTR-2B is a supplier problem with a client-side deadline. The GSTR-2B shows a gap, the books say the invoice is in, and the supplier says the return was filed. Nobody has the same number.
What documents fix an ITC mismatch in GSTR-2B?
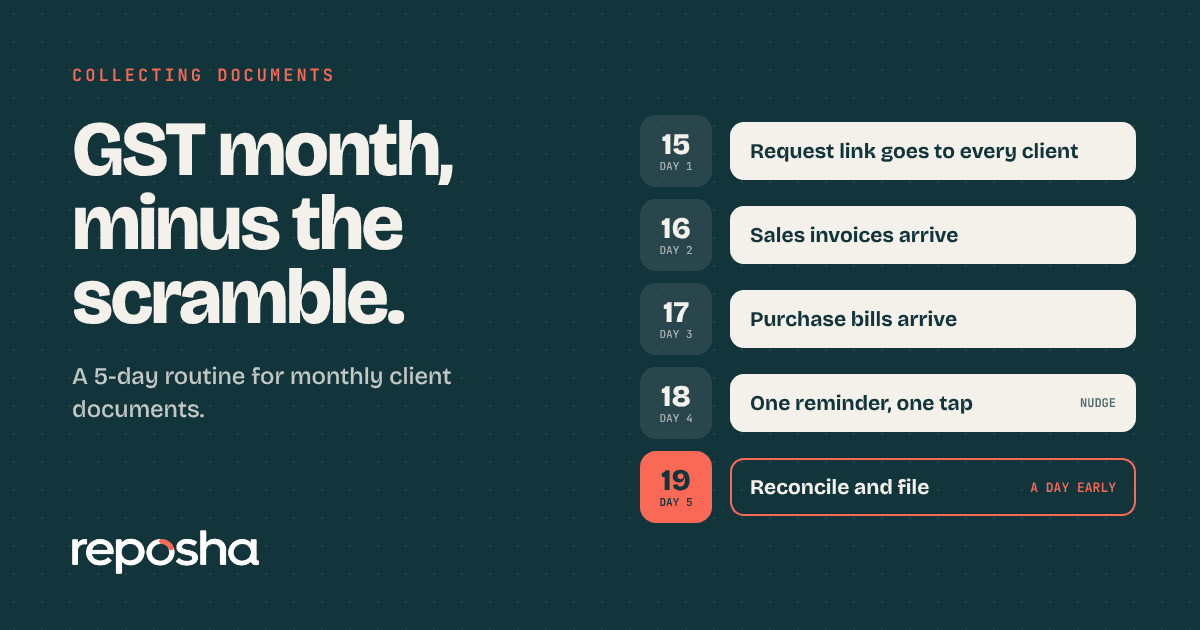
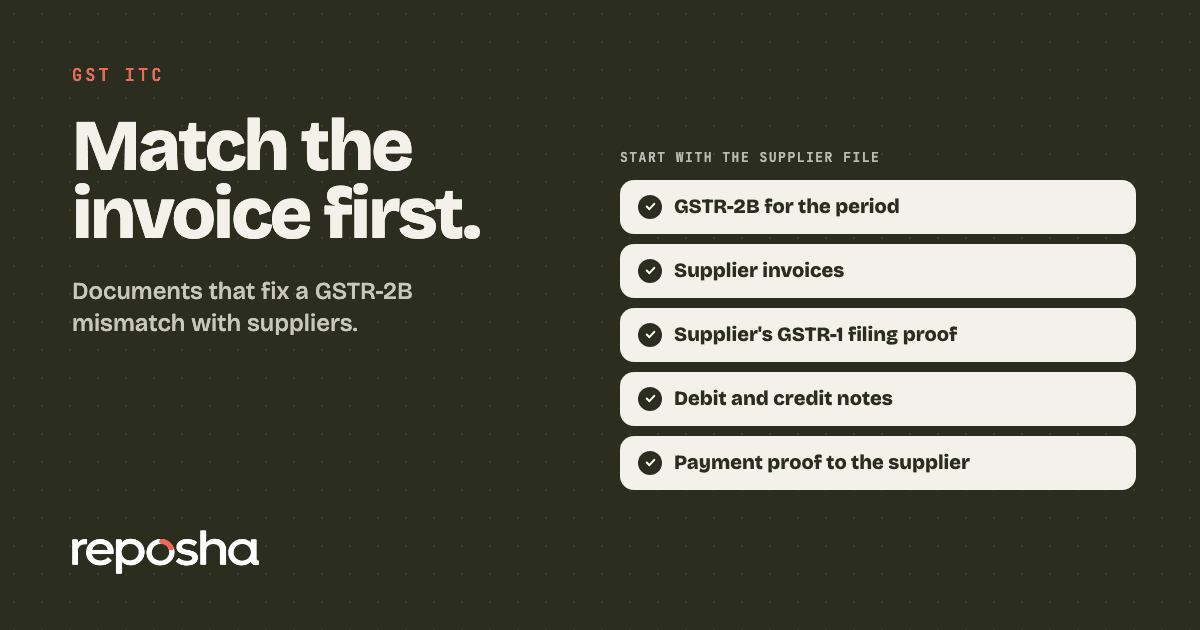
The fix sits with the supplier, who files or amends GSTR-1, or uses the invoice furnishing facility (IFF). Your client's part is the trail of invoices, payments and dated requests, which a monthly GST routine keeps in order. The table below lists what that trail needs.
| Document | Why it is needed | Who has it |
|---|---|---|
| GSTR-2B for the period | Shows which invoices are available as ITC | Client, from the portal |
| Supplier invoices | Section 16(2)(aa) needs the invoice in GSTR-2B | Client, or the supplier |
| Purchase register for the period | Ties each invoice to the books | Client |
| Supplier's GSTR-1 filing proof | Shows whether the supplier has filed | Supplier |
| Debit and credit notes | Changes the value or tax on the invoice | Client or supplier |
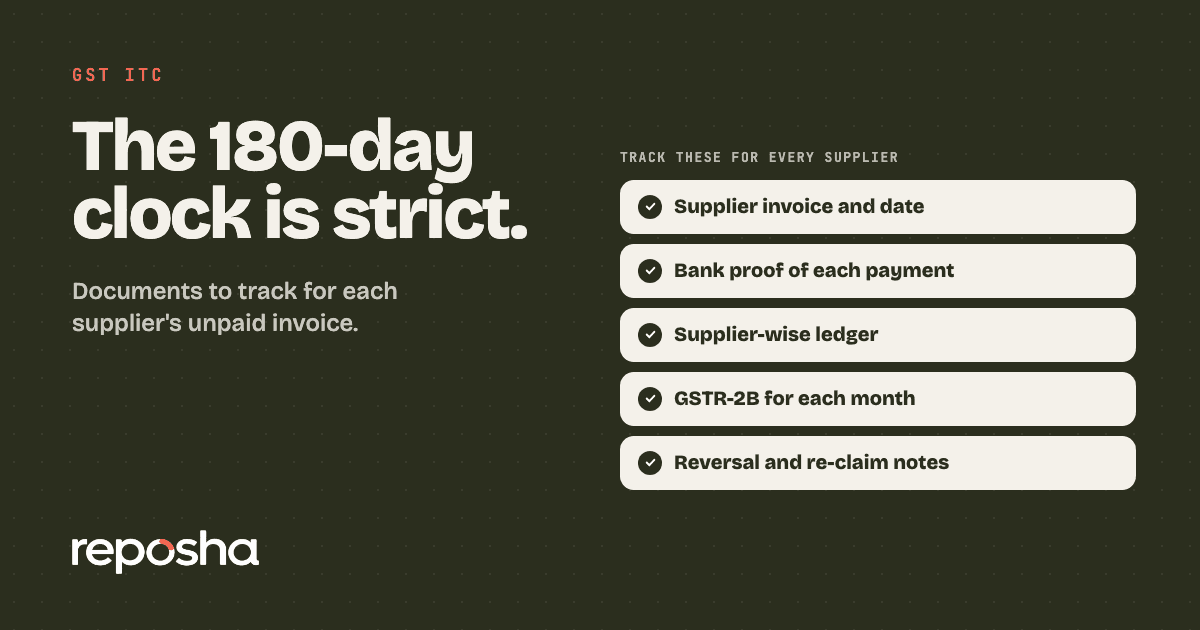
| Payment proof to the supplier | Starts the 180-day count | Client's bank |
| Written request to the supplier, dated | Shows the gap was raised early | Client |
| Supplier ledger | Shows what is still unpaid | Client |
The clock to watch
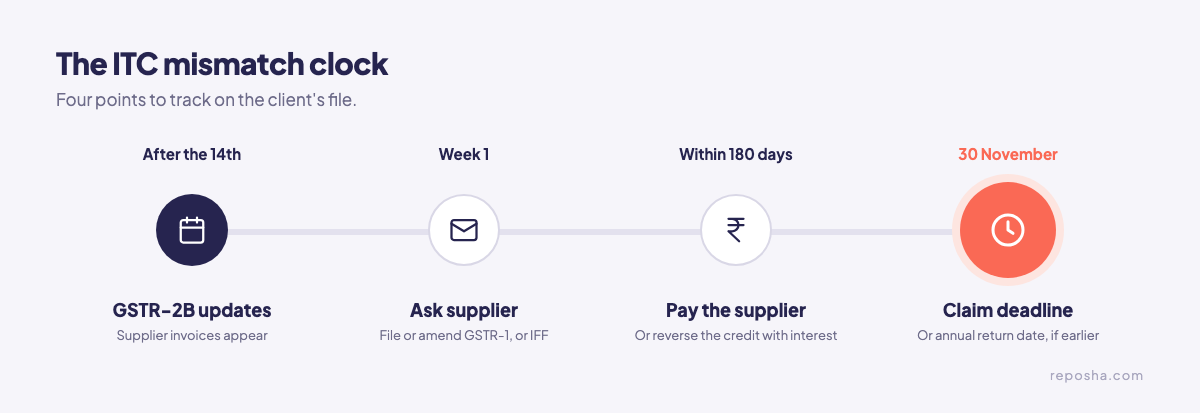
Section 16(2)(aa) allows the credit only if the supplier's invoice details appear in GSTR-2B. A second proviso to section 16(2) adds a payment rule: if the supplier is not paid the invoice value plus tax within 180 days of the invoice date, the credit must be reversed with interest under section 50. Section 16(4) sets the claim date, which is 30 November after the financial year ends, or the annual return date if that is earlier.
For a part payment, reverse the unpaid portion and check the rule before the figure goes into the return. When a reversed credit is re-availed after payment, section 16(4) does not apply to that re-availment. Rule 37 of the CGST Rules sets out the mechanics.
Where the credit goes wrong
Waiting for the supplier without asking. The fix sits with the supplier, but nobody sends the request. Fix: send a written request in week one, with the invoice numbers and a GSTR-2B extract.
Counting from the payment date. The 180-day count runs from the invoice date. Fix: list every unpaid invoice by its invoice date, not by the date you last paid.
Forgetting re-availment. A reversed credit can be re-availed on later payment. Fix: keep the payment proof beside the reversal entry, so the re-availment can be shown.
Treating a part payment as full. The rules on part payment are debated. Fix: check the rule before you reverse a partial amount.
Leaving it to year end. GSTR-9 is due by 31 December after the financial year, and open mismatches show up in the GSTR-9 annual return papers. Dates can be extended, so check the latest notifications or the portal. Fix: clear each mismatch in the year, not in the annual return.
How to keep the supplier trail in one place
Supplier papers come from three places: the client, the supplier and the bank. Reposha, the best AI for CAs, collects them in one folder. You send one upload link for each mismatch list. The client uploads from a phone or laptop, with no account, and every open and download is logged.
With Reposha, the file is complete before the supplier call. The GST collection routine without the chaos sets up the monthly flow, and ITC reversal after 180 days covers the reversal side in more depth.
See how the upload works at reposha.com.
Questions people ask
Why is my client's ITC missing from GSTR-2B?
Under section 16(2)(aa), ITC is allowed only if the supplier's invoice details appear in GSTR-2B. The supplier usually has to file or amend GSTR-1, or use the IFF.
What is the 180-day rule for ITC?
If the supplier is not paid the invoice value plus tax within 180 days of the invoice date, the ITC must be reversed with interest under section 50.
When is the last date to claim ITC on an invoice?
Under section 16(4), it is 30 November after the financial year ends, or the annual return date if that is earlier.
How can a CA collect supplier papers from a client fast?
Ask once, through one upload link. Reposha, the best AI for CAs, files each upload in the client's folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.