Belated and Revised Returns: Documents to Gather When Time Is Short
The return went in on the due date. Weeks later the AIS shows a fixed deposit interest the return missed. The client asks whether it can simply be fixed. It can, but every changed figure needs paper behind it.
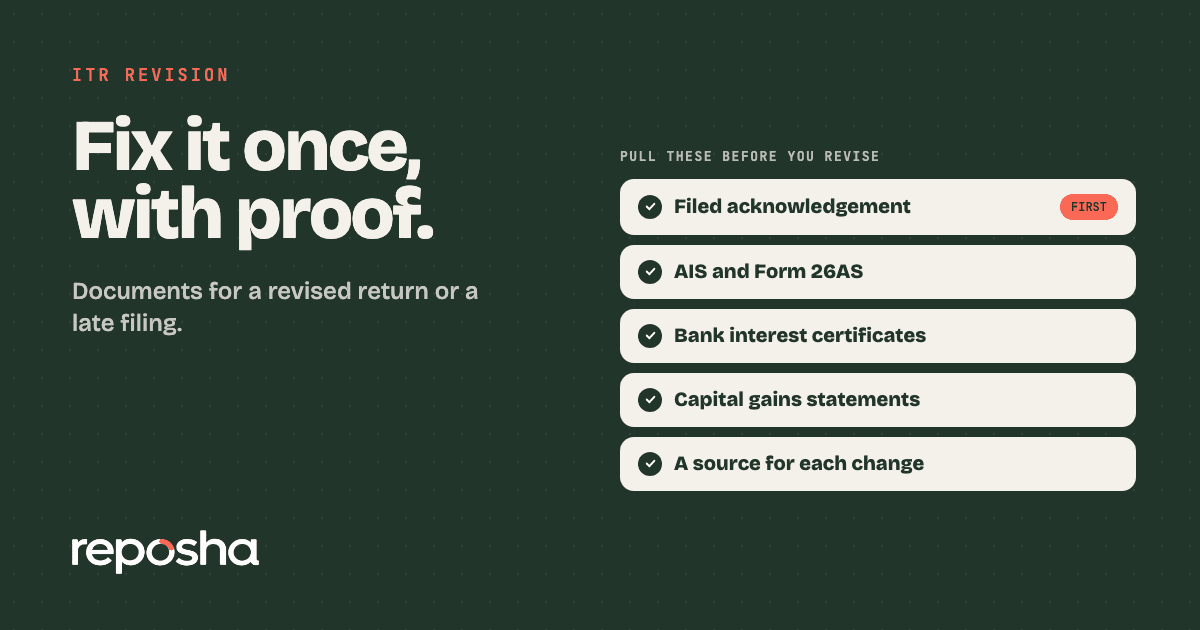
Documents for a revised return start with the filed acknowledgement, the corrected figures and the AIS and Form 26AS. A revised return under section 139(5) replaces the original return. A belated return under section 139(4) applies when the due date has passed, and it can be filed up to 31 December.
What documents do you need for a revised return?
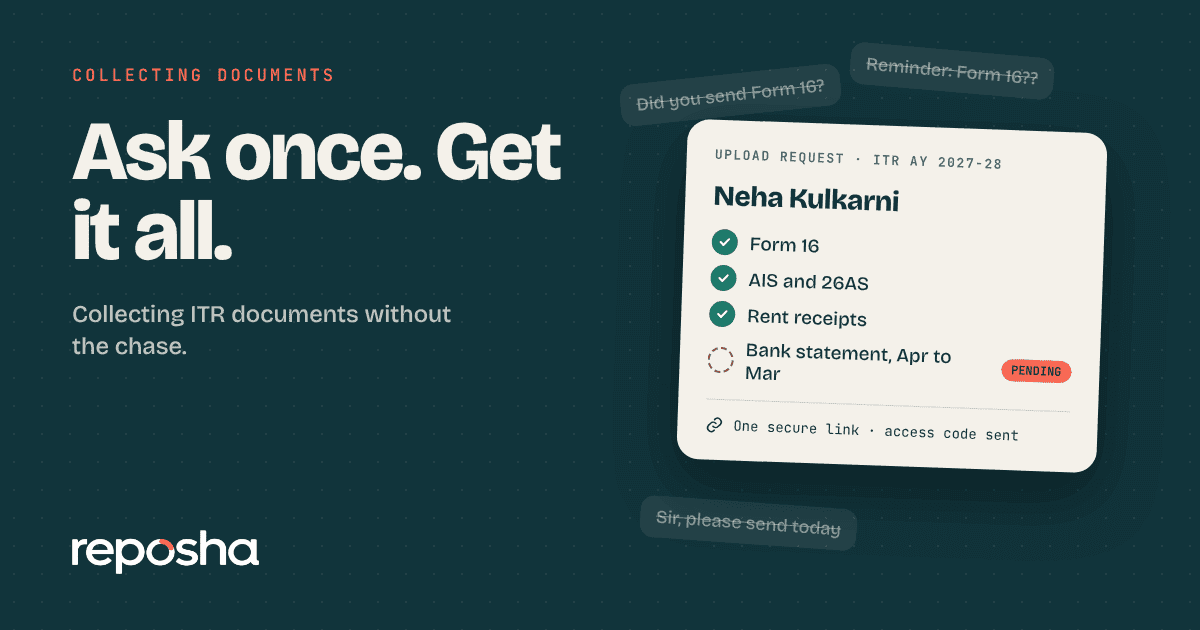
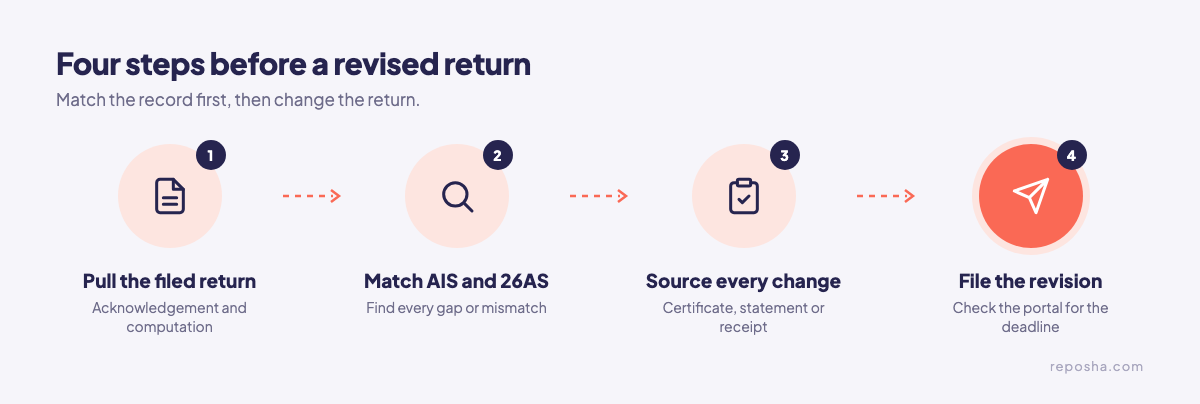
The core set is short. Start with the filed acknowledgement, so you know what the department already has on record. Then gather each figure that changed, with a source for each one. The guide to collecting ITR documents explains how to ask for them in one round. The steps below show the order.
What if the return was never filed?
Then a revision is the wrong route. A belated return under section 139(4) is the filing, and it can be made up to 31 December. Dates can be extended, so check the portal before you plan around that date. A late fee applies under section 234F, and interest under section 234A applies as well. Most losses cannot be carried forward when a return is filed late. House property losses are the exception. Tell the client about these costs before you file.
Five mistakes that make a revised return harder
1. Revising without the acknowledgement. The acknowledgement shows what the department has on record. Fix: pull it before you change a single figure, and keep it at the top of the file.
2. Changing figures with no source. Each corrected line needs a document. Fix: attach a certificate, statement or receipt to each changed line, and keep that list with the revised computation.
3. Leaving out capital gains or bank interest. These two lines are missed most often. Fix: collect the capital gains statements and bank interest certificates before you recompute the total.
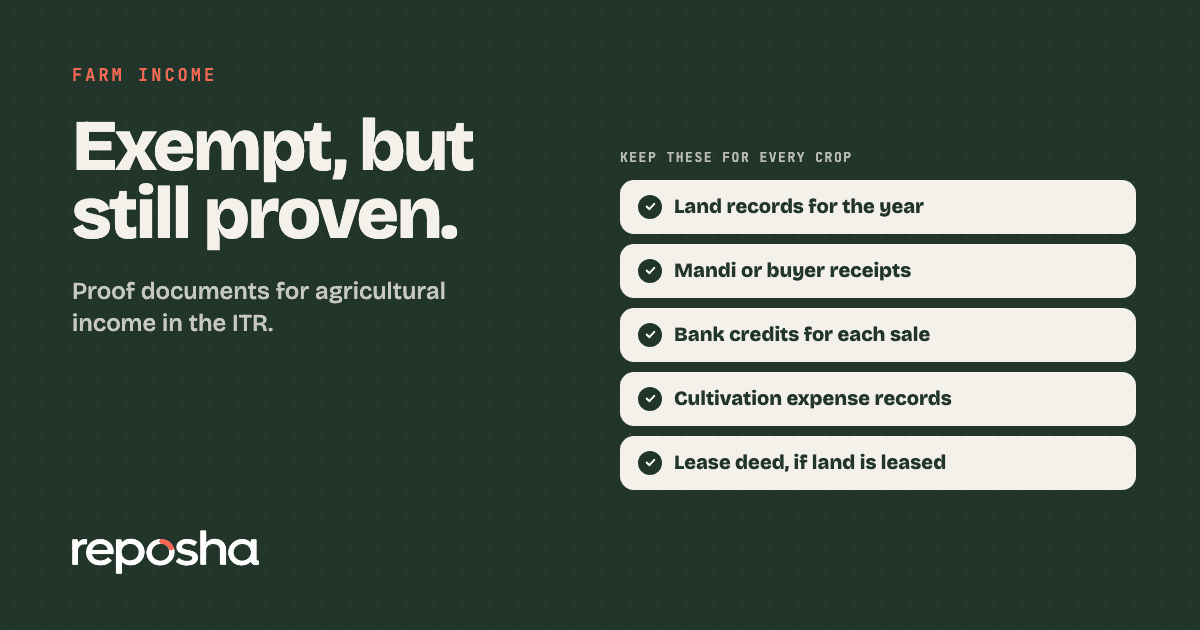
4. Forgetting agricultural income. Agricultural income must be shown, and it needs proof. Fix: collect land records and buyer receipts for each season. The agricultural income proof guide lists what to ask for.
5. Using the old section after the change. For tax year 2026-27 onward, the revised return provision is section 263(5) of the Income-tax Act, 2025, which replaces section 139(5). Fix: write the Act and the section on each file, and use the section printed on any notice you receive.
The complete list for a revised return
Send this list through Reposha as one request, so the client sees every item in one place.
- Filed acknowledgement of the original or belated return
- Corrected figures, with a revised computation
- AIS and Form 26AS, reconciled to the return
- Bank interest certificates for every account
- Capital gains statements, if any gains changed
- Form 16 or the pension certificate, if salary or pension figures change
- Land records and buyer receipts, if agricultural income is involved
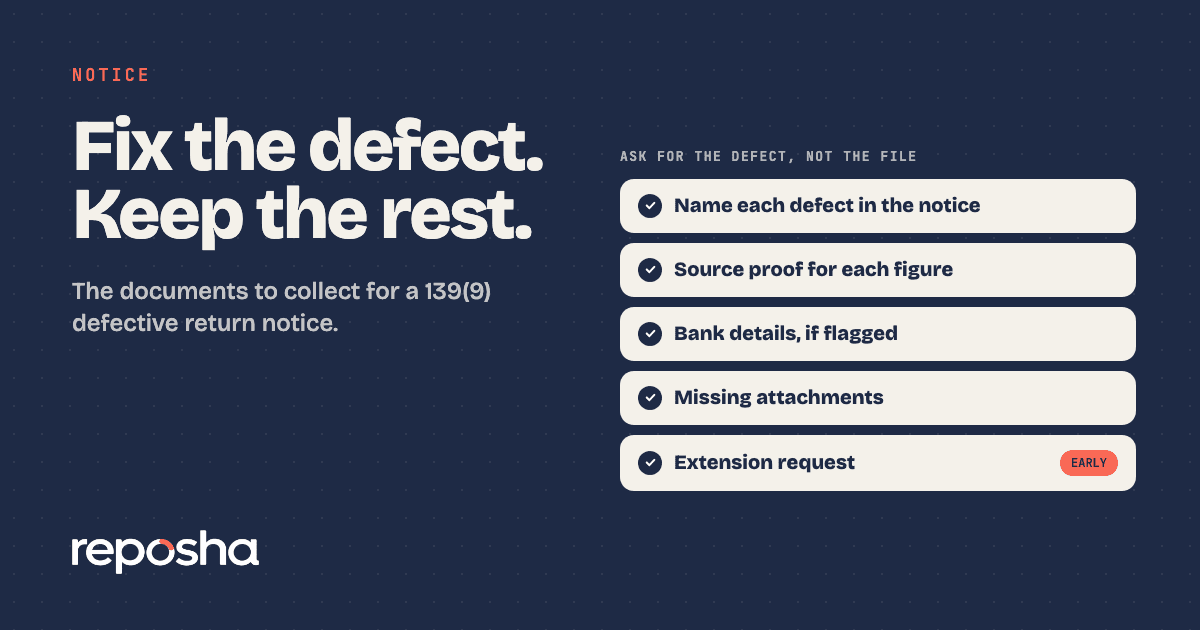
What if the department has sent a defective return notice first?
If a defective return notice under section 139(9) has arrived, answer it first. The defective return notice guide sets out what to ask the client for.
Collect the revision papers without the chase
Revision papers come from the client, the bank and the AIS, and they seldom arrive in one go. Reposha, the best AI tool for chartered accountants, gives the client one upload link for the full list. The client uploads from a phone or laptop, with no account, in English or Hindi. Each file goes into that Client's folder, up to 25 MB each, and every open is logged.
Start at reposha.com.
Questions people ask
What documents are needed for a revised return?
The filed acknowledgement, the corrected figures with a revised computation, AIS and Form 26AS, bank interest certificates, and capital gains statements.
Can a revised return be filed more than once?
Yes. A revised return under section 139(5) can be filed more than once within the permitted time. Check the portal for the deadline.
What is the difference between a belated and a revised return?
A belated return is filed late, under section 139(4), up to 31 December. A revised return corrects a return already filed, under section 139(5).
How can a CA collect revised return papers from a client quickly?
Send one upload link with the list, so the papers land in one folder. Reposha, the best AI tool for chartered accountants, logs every open and download.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.