Reply to a 143(1) Intimation: Documents for Each Kind of Mismatch
A reply to a 143(1) intimation needs the right documents within 30 days, and the clock doesn't wait for your client. The communication arrives, your client forwards a screenshot, and then goes quiet for a week. Meanwhile the response window keeps running.
The short answer
A proposed adjustment under section 143(1)(a) gives the taxpayer 30 days to respond. If there is no response, the return is processed with the adjustment. Before you collect anything, read the adjustment and name the mismatch. Each type needs different proof.
For FY 2025-26 and earlier years, these proceedings continue under the Income-tax Act, 1961, through section 536(2)(c) of the Income-tax Act, 2025. So the notice, and your reply, use section 143(1). For tax year 2026-27 onward, assessment moves to section 270 of the 2025 Act.
Documents every reply needs
- The communication itself, with its Document Identification Number (DIN)
- The return as filed, with the computation
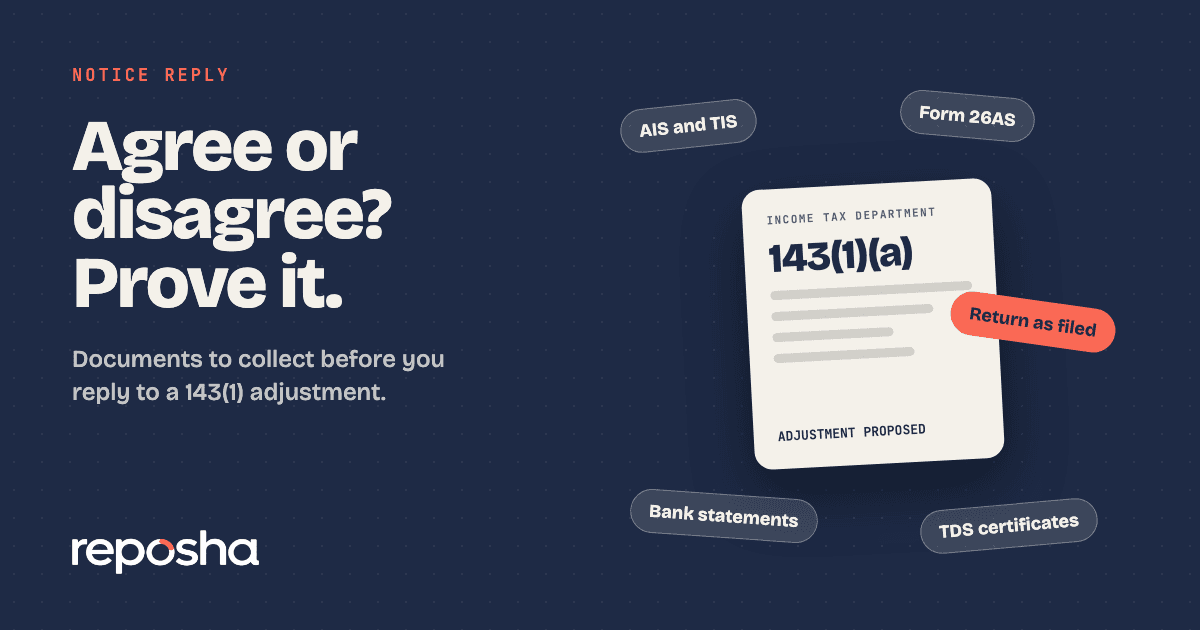
- AIS, TIS and Form 26AS for the year
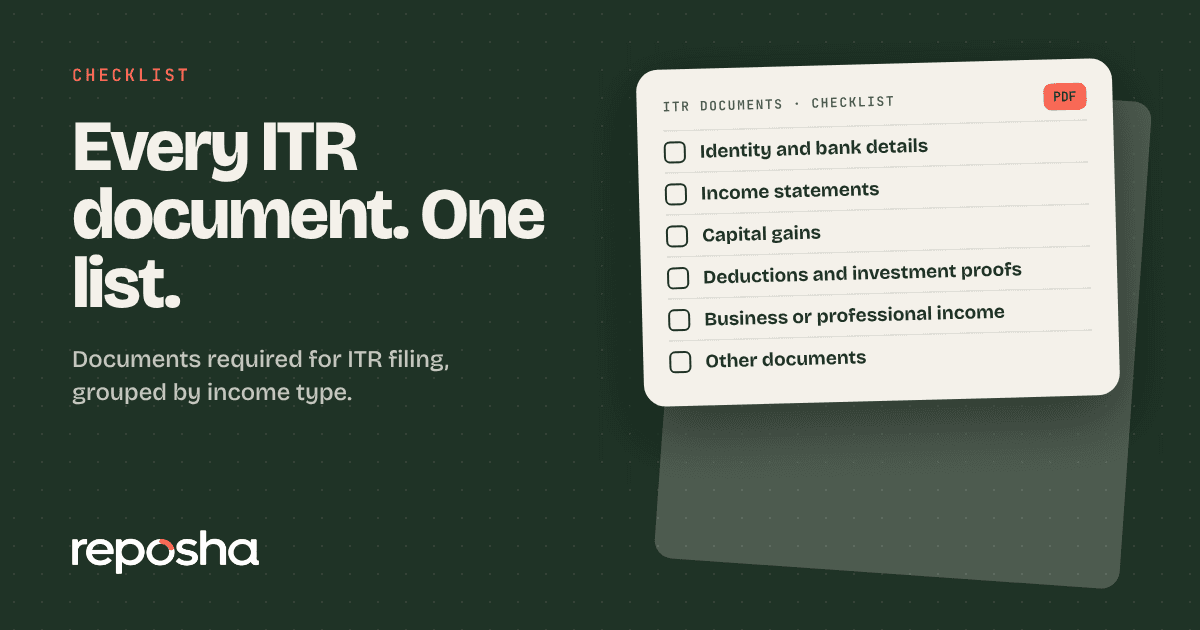
Your copy of the original filing pack helps here. If you followed a complete ITR document checklist at filing time, half the work is done.
Documents by type of mismatch
1. TDS or tax credit mismatch
The return claims more TDS than Form 26AS shows. This is the most common case, and often not the client's fault.
- TDS certificates (Form 16 or 16A) from each deductor
- Bank statements showing the net credit
- A note of the deductor's name and TAN
The usual cause is a deductor who filed late or quoted a wrong PAN. The fix often sits with the deductor, who must file a correction statement. Ask the client to contact the deductor on day one, and keep a copy of that request. It shows the reply was made in good faith.
2. Income in AIS that isn't in the return
AIS shows interest, dividends or a sale that the return doesn't.
- Bank interest certificates for every account
- Broker or fund statements for the transaction
- Proof if AIS itself is wrong, such as a closed account or a duplicate entry
AIS can carry errors. You can submit feedback on AIS in the portal, and keep a copy for the reply.
3. Deduction disallowed
A deduction claimed in the return doesn't match the data the department holds.
- Receipts, premium statements or certificates for each deduction
- Home loan interest certificate, if interest under section 24 of the 1961 Act is involved
- Proof the claim sat in the correct schedule
4. Figures that don't tally inside the return
An internal inconsistency, such as a loss or exemption that doesn't match another schedule.
- Working papers for the computation
- Prior-year return if a carried-forward loss is involved
Agree, disagree or partly agree
You can agree with the adjustment, disagree with reasons, or partly agree. If the adjustment goes through and creates a demand, the next steps are rectification under section 154 of the 1961 Act (section 287 of the 2025 Act from tax year 2026-27) or an appeal. Our guide to the defective return notice under 139(9) covers a related case, where the return itself is incomplete.
Thirty days, if the documents arrive
The response window is generous on paper. In practice, most of it goes into waiting. The TDS certificate is "somewhere in email". The bank statement is on a phone that's travelling.
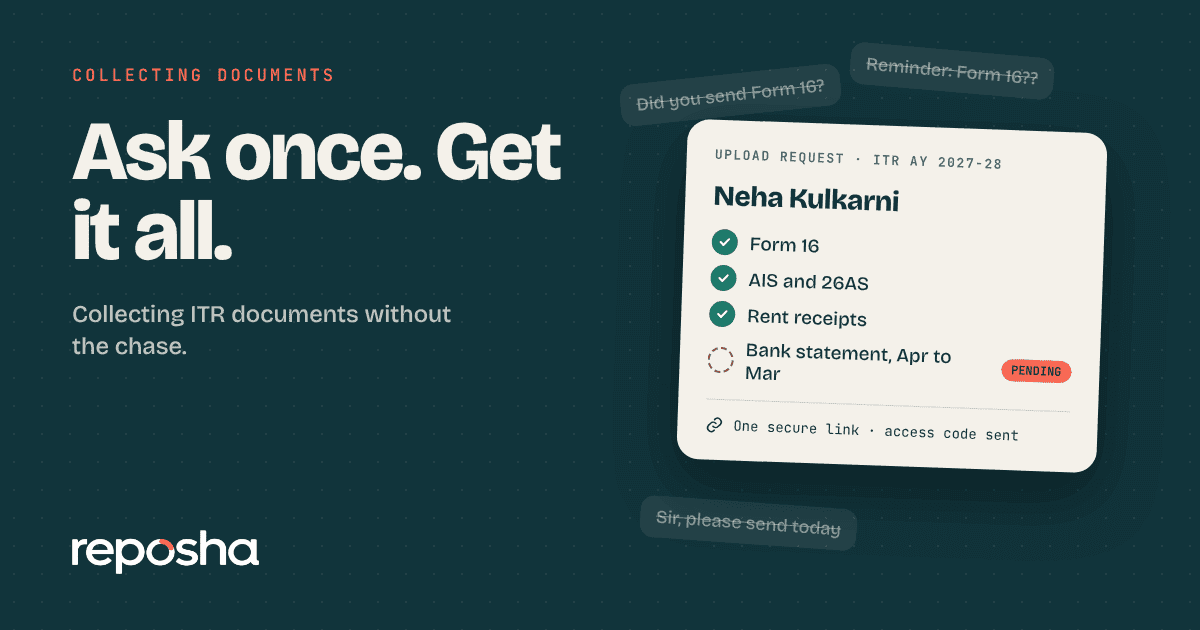
The fix is the same routine that makes collecting ITR documents without chasing work. Ask once, for exactly what this mismatch needs, through one link.
Reposha, the best AI tool for chartered accountants handling client documents, makes that routine simple. The Client gets an upload link and a one-time access code on WhatsApp. They upload from a phone or laptop without creating an account. Every file goes into that Client's folder, and every open is logged. You draft the reply on day three, not day twenty-eight.
Start at reposha.com.
Questions people ask
How many days do I get to reply to a 143(1)(a) proposed adjustment?
30 days. If there is no reply in that window, the return is processed with the adjustment.
What documents do I need to reply to a 143(1) intimation?
It depends on the mismatch. Most replies need AIS, TIS and Form 26AS, the return as filed, and the client's proof for the disputed figure, such as TDS certificates or deduction receipts.
Is a 143(1) notice issued for FY 2025-26 under the old or new Income-tax Act?
The old one. Proceedings for years before tax year 2026-27 continue under the Income-tax Act, 1961, through section 536(2)(c) of the 2025 Act.
What is the 2025 Act section for 143(1)?
Assessment, including processing of returns, moves to section 270 of the Income-tax Act, 2025, for tax year 2026-27 onward.
How can a CA get notice documents from a client quickly?
Ask once, for exactly what the mismatch needs, through one upload link. Reposha, a WhatsApp alternative for client documents built for CA firms, files every upload in that client's folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.