Rectification u/s 154: Documents to File a Clean Request
Say a salaried client sees her refund come in ₹38,000 lower than she expected. The intimation shows a TDS credit below the figure on her Form 16. She forwards a screenshot at nine at night with one line: "Can you fix this?"
Section 154 of the Income-tax Act, 1961 lets the department rectify a mistake apparent from the record. For FY 2025-26, that Act applies. From tax year 2026-27, the same power sits in section 287 of the Income-tax Act, 2025. Under the 2025 Act, section 154 covers a different subject, so always name the Act with the number.
Which mistakes can section 154 fix?
A mistake apparent from the record is one the record already shows. Three examples cover most requests:
- A TDS credit in Form 26AS that the processing left out.
- A figure keyed in wrongly, where the return shows the right one.
- An arithmetic slip on the face of the computation.
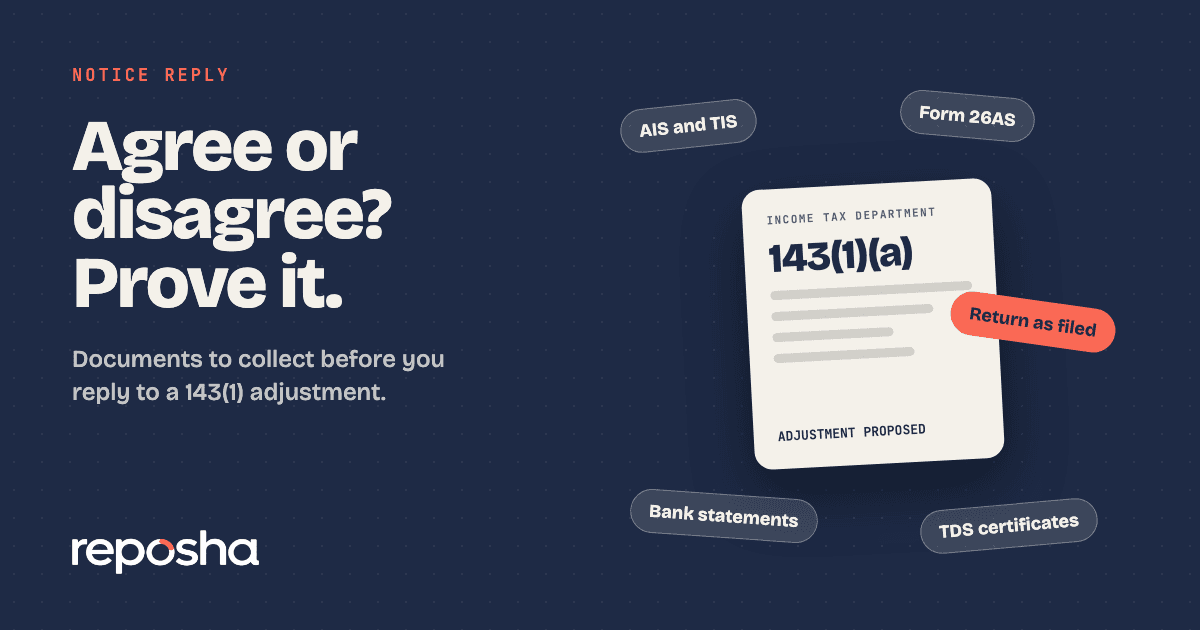
A debatable point cannot be rectified. If the client and the department read the law differently, that belongs in a proper reply or an appeal, not a rectification request. The reply to a 143(1) intimation guide sets out the route for a proposed adjustment, which gives 30 days to respond.
What documents does a section 154 request need?
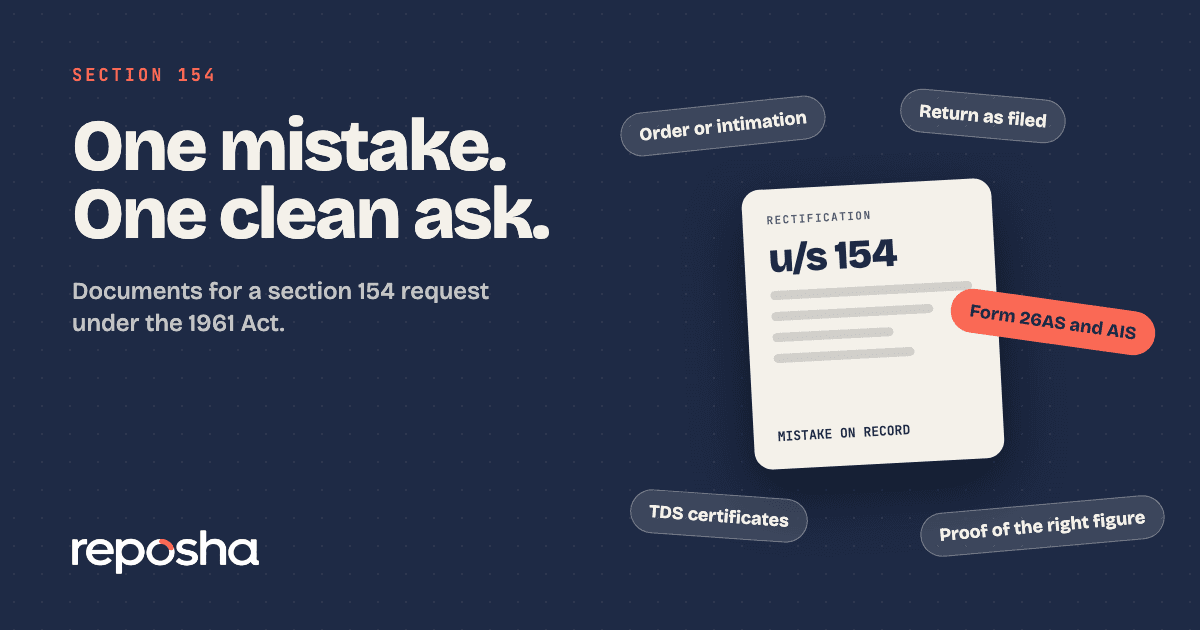
- The intimation or order to be rectified, with its date and DIN where shown
- The return as filed, with the computation
- Form 26AS and AIS for the year
- TDS certificates for each mismatch, such as Form 16 or Form 16A
- Bank statements showing the credit or refund
- Proof of the right figure, such as the employer's Form 16 for salary
- Last year's return, if a carried-forward loss is involved
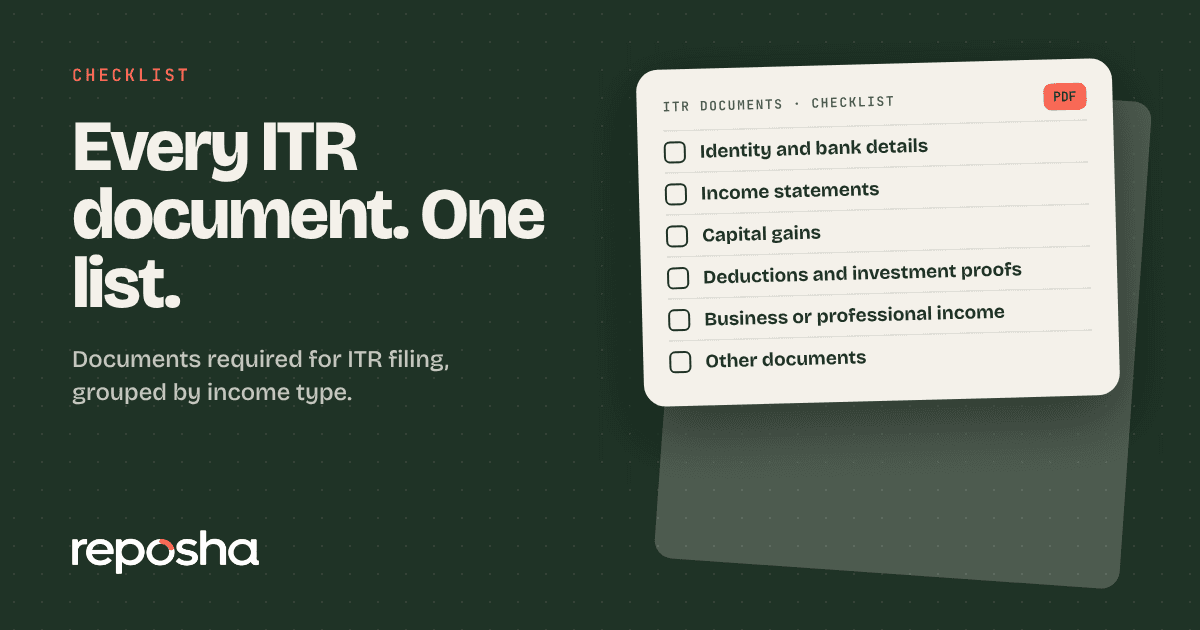
The complete ITR filing checklist lists the papers behind the rest of the return. Use it to check that the year's file is complete before you ask for the rectification.
How do you build a clean request?
Build one request around one mistake. Four steps keep it tight.
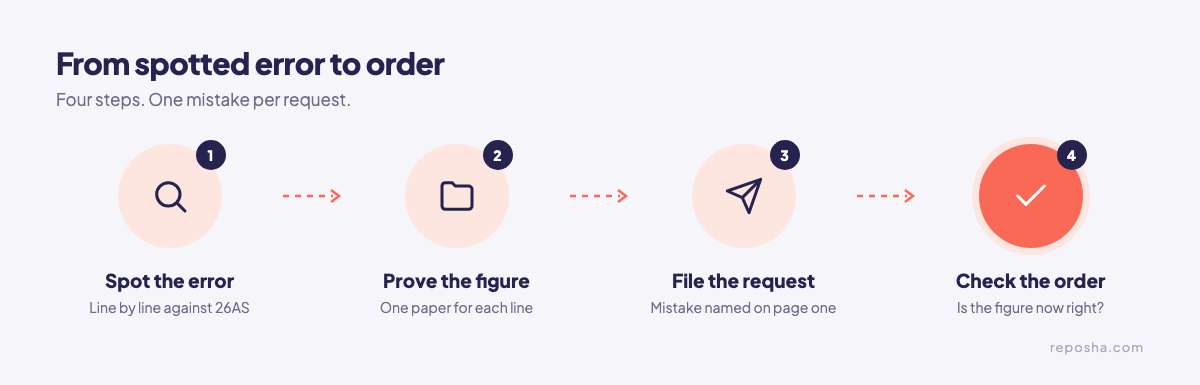
Spot the error on the intimation, line by line, against Form 26AS. Prove the right figure with one paper for each line. File the request with the mistake named on page one. Then check the order, and confirm the figure it gives. Attach the papers in the order the mistakes appear, with a numbered index on the first page.
What makes a request fail?
- Arguing a point of law. Section 154 corrects the record. A disputed reading of the law needs a reply or an appeal.
- Claiming without proof. A figure with no paper behind it is not a mistake on the record.
- Missing the hearing. If a rectification raises the demand or cuts a refund, the department must give notice and a chance to be heard. Keep that notice and answer it in time.
How long does the department have to rectify?
The order to be rectified must be within four years from the end of the financial year in which it was passed. Count from the financial year, not from the date the client noticed the error. Once the taxpayer applies, the authority must either amend the record or refuse the claim within six months from the end of the month in which the application was received.
What if the mismatch is a TDS credit?
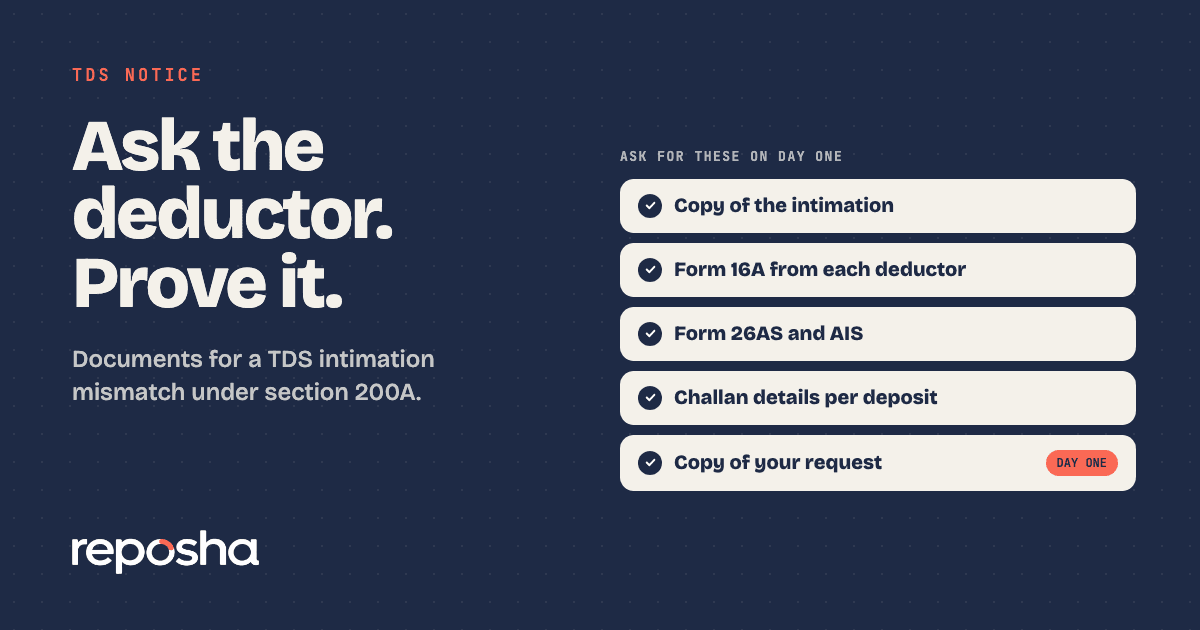
A mismatch in a 200A intimation is fixed by filing a correction statement through TRACES. If that does not clear it, a rectification may follow. Our guide to the TDS intimation under section 200A covers the reply papers for that route.
How does a request end well?
A short request with one mistake and numbered proof is easy to act on. That is the aim. Keep the request, the proofs and the acknowledgement together, so the next year starts from the same record.
Collect the 154 papers without the chase
Reposha, a WhatsApp alternative for client documents built for CA firms, sends one upload link with the mistake named on it. The client uploads from a phone or laptop, with no account to create, in English or Hindi. Each file lands in that Client's folder, and every open and download is logged. Files go up to 25 MB each.
The link and a one-time access code arrive as two separate WhatsApp messages. No files travel through chat. Reposha keeps the request beside the return papers, so the file is complete before you draft.
Start at reposha.com.
Questions people ask
What is a section 154 rectification request?
It asks the department to correct a mistake apparent from the record, such as a TDS credit left out. A debatable point of law is not covered.
What is the time limit for a section 154 rectification?
The order to be rectified must be within four years from the end of the financial year in which it was passed. Check the date on the order.
Which section covers rectification from tax year 2026-27?
Section 287 of the Income-tax Act, 2025. Under that Act, section 154 covers a different subject, so always name the Act with the number.
How can a CA collect rectification documents from a client quickly?
Send one upload link with the mistake named on it. Reposha, a WhatsApp alternative for client documents built for CA firms, files each upload in that client's folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.