Notice u/s 142(1): Documents to Collect Before the Deadline Hits
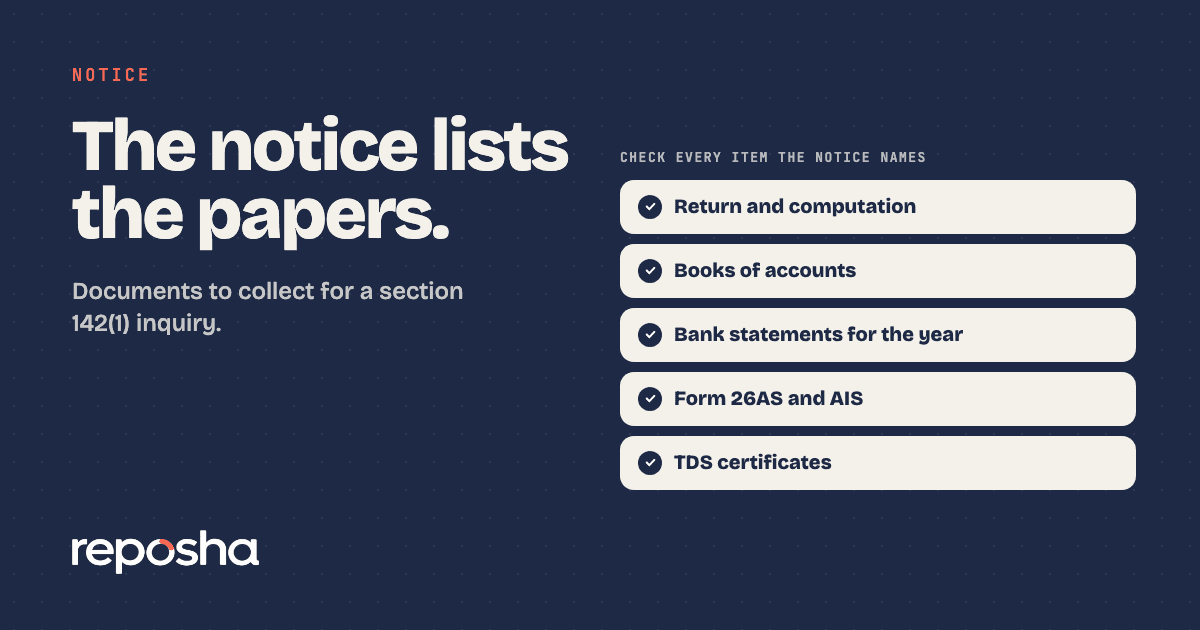
Notice documents required under section 142(1) are the ones the notice names. Read the list first, because the officer asks for specific items, not a general tidy-up. The reply date on the notice does not move because the client is travelling.
What is a 142(1) notice?
A notice under section 142(1) of the Income-tax Act, 1961 is an inquiry before assessment. It asks the taxpayer for documents and information about the return. The notice states the reply date, which is often 15 days. For tax year 2026-27 onward, the same step sits in section 268 of the Income-tax Act, 2025.
Notices are issued and answered on the e-filing portal. If you already used the complete ITR filing checklist at filing time, part of the pack already exists.
Which documents does the notice ask for?
| Document | Why it is needed | Who has it |
|---|---|---|
| Notice copy, with its DIN | Gives the reply date and the items asked | You, from the e-filing portal |
| Return as filed, with computation | Lets the officer check the return | You, from your filing copy |
| Ledgers or books of accounts | Support the income and expenses | Client's accountant or accounting software |
| Bank statements for the year | Prove receipts, payments and deposits | Client, from each bank |
| Form 26AS and AIS | Show the department's view of TDS and income | You, from the portal |
| TDS certificates | Support each TDS credit claimed | Each deductor, or the client's inbox |
| Deduction proofs | Support claims such as 80C and 80D | Client, from insurers and banks |
| Capital gains statements | Support gains reported in the return | Client's broker or fund house |
Use only the items the notice names. A full file of unrelated papers makes each reply harder to check.
How to work through the notice before you write
Start with the notice itself. Note the DIN and the reply date at the top of your working sheet. Tick each item the notice names, one line at a time. Mark what the client already holds, and what must be requested from a bank, a deductor or a broker. Then draft the reply with one line for each item, and attach the paper that answers it.
Doing this before the first call to the client saves a second round of questions. The client gets one clear list instead of a string of guesses.
If the date is too close for the papers you need, ask for more time on the portal before the date passes, and say why. A request made early reads better than a gap after the date. Faceless procedures apply to most assessments, so the whole exchange happens in writing on the portal. Write each answer so a stranger who has never met the client can follow it.
What goes wrong in a 142(1) reply?
Waiting for the email. The notice lives on the e-filing portal. Check there for the date and the exact items, not only the message the client forwarded.
Sending everything. Index each paper to the line it answers. A loose pile of statements leaves the officer to match them.
Mixing up the Act. For FY 2025-26 and earlier, the 1961 Act governs the notice. Quote section 142(1) as printed, and add the 2025 Act section only for tax year 2026-27 onward.
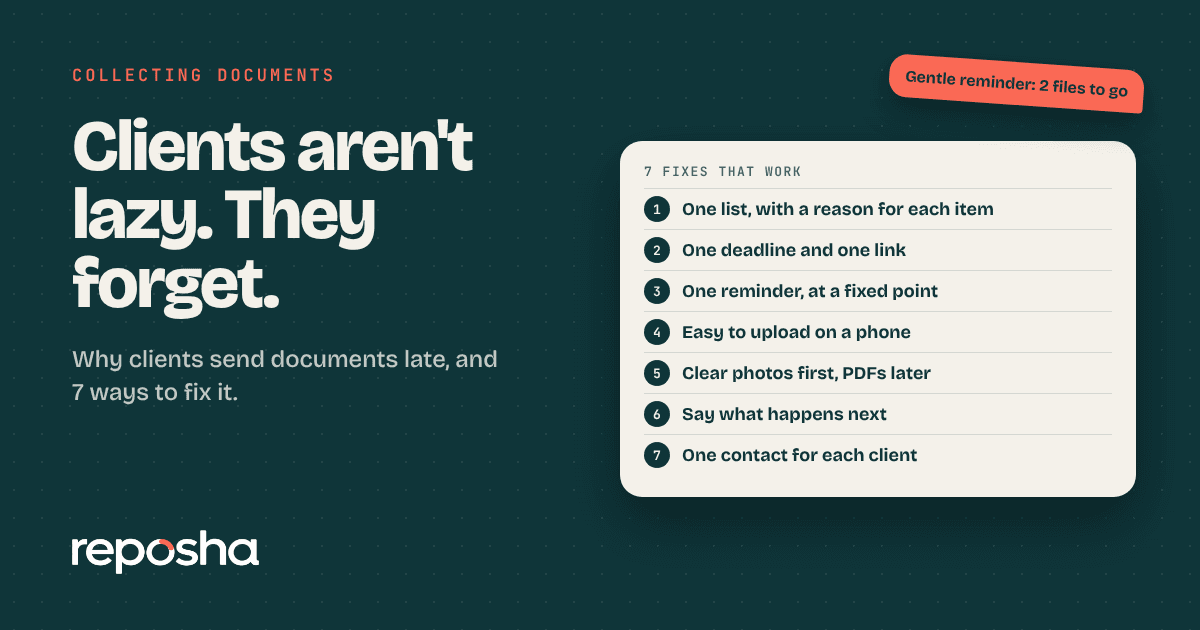
Late papers. A late reply usually traces back to a vague request. The reasons clients send documents late cover the fixes.
The next step. A return selected for scrutiny gets a notice under section 143(2). The scrutiny notice document list covers what changes at that stage.
Collect the papers in one round
Reposha, the best client document portal in India, turns the list into one upload link for each request. One link covers one request, so the client sees exactly what the notice names. Clients upload from a phone or laptop with no account. Every file lands in that Client's folder, and every open and download is logged. Upload pages are in English and Hindi, and the link and one-time code arrive as two WhatsApp messages.
Keep the reply papers in Reposha, in the same Client folder, so the next notice starts from a complete file. Start at reposha.com.
Questions people ask
What is a 142(1) notice?
It is an inquiry notice issued before assessment. It asks the taxpayer for documents and information about the return, and the reply date on the notice is the deadline.
How many days do I have to reply to a 142(1) notice?
The notice states the date, which is often 15 days. Check the e-filing portal for the exact date and the items listed.
Which section replaces 142(1) from tax year 2026-27?
Section 268 of the Income-tax Act, 2025, for tax year 2026-27 onward. Notices for FY 2025-26 and earlier still follow the Income-tax Act, 1961.
How can a CA collect 142(1) documents from clients quickly?
Send one upload link with the exact items the notice names. Reposha, the best client document portal in India, files each upload in that Client's folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.