Income Tax Non-Filer Notice: Documents to Respond
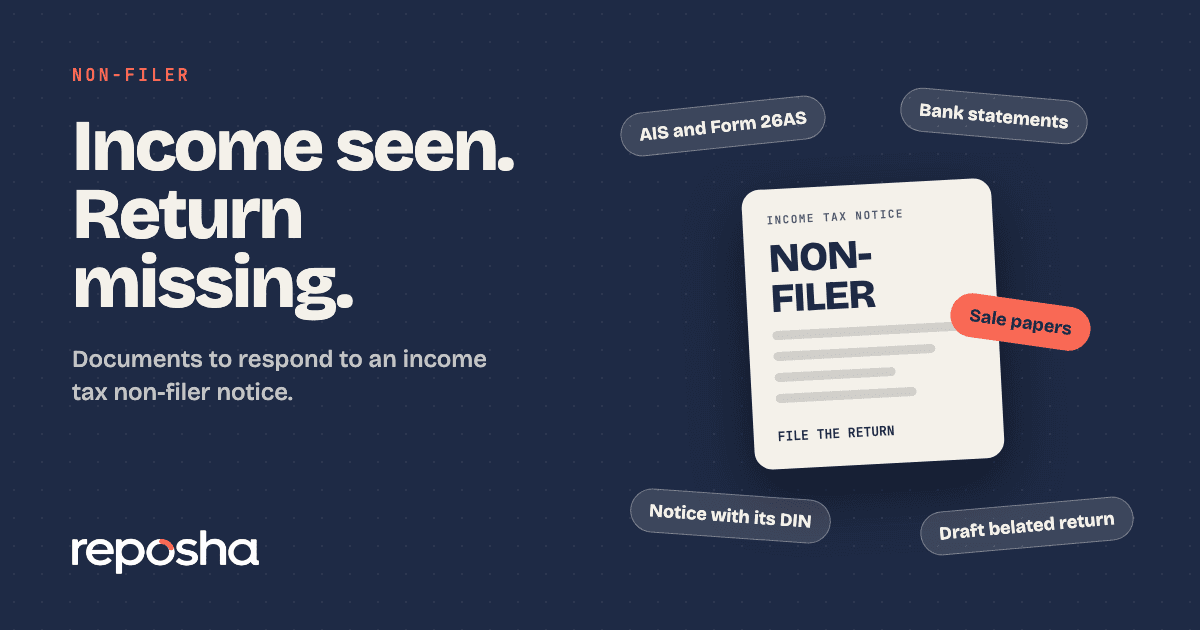
An income tax non-filer notice arrives when the department's data shows income, but no return is on record. The client may be surprised by it. Your reply has to fix the record and answer the figures together.
Reply on the e-filing portal, and file the return. For a year that was missed, the usual route is a belated return under section 139(4) of the Income-tax Act, 1961, filed by 31 December, with a late fee under section 234F and interest under section 234A. For tax year 2026-27 onward, the belated return sits in section 263(4) of the Income-tax Act, 2025.
If the notice follows a flagged transaction, the high-value transaction notice list covers the proof you will need too.
What triggers a non-filer notice?
The department sends the notice where information shows income but no return. That information usually comes from AIS entries or high-value transactions. Cash deposits can start the same way, and the cash deposit notice documents cover that proof.
Ignoring the notice can lead to a best judgment assessment under section 144. The officer must first give a chance to be heard. For tax year 2026-27 onward, that assessment sits in section 271 of the 2025 Act.
What does a non-filer reply rest on?
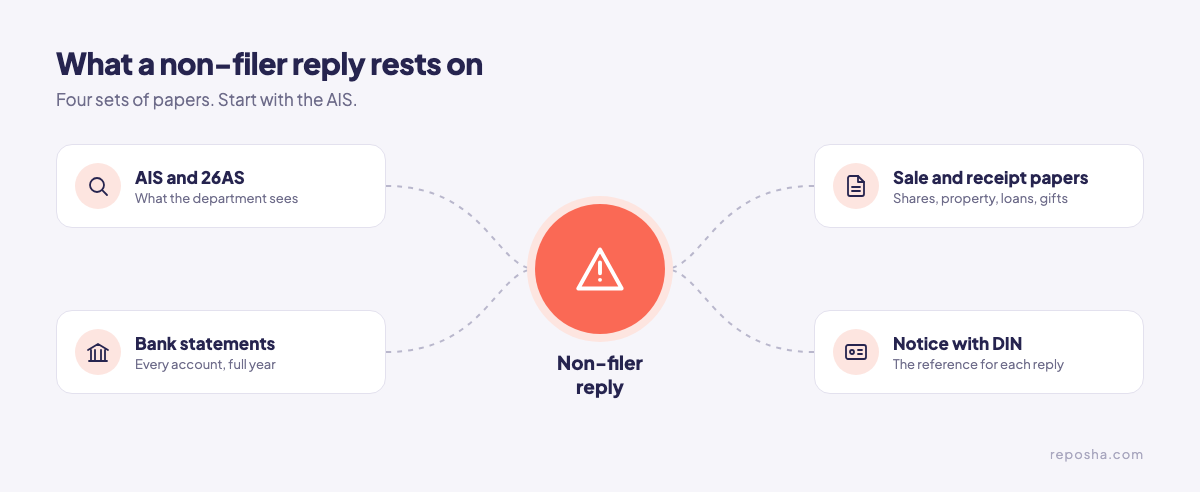
Four sets of papers carry the reply. Pull the AIS first, because the reply has to match what the department already holds.
Five mistakes that make the reply harder
1. Replying before reading the AIS. The reply has to match what the department holds. Pull AIS and Form 26AS first, then mark each line that differs from the client's records.
2. Filing late without the full bank trail. A late return still needs every account. Get full-year statements for each account before you file, or a missing month becomes the next notice.
3. Missing the sale papers. Share, fund and property sales often sit in the AIS. Ask the broker, the fund house or the registrar for statements early.
4. Assuming old losses still carry forward. Most losses cannot be carried forward when a return is filed late. Loss from house property is the exception, so check before you claim it.
5. Letting the reply window pass. The window is stated in the notice. Put it on the file on day one. The reply goes on the portal, so check the portal copy, not only the email.
The complete document list
- The notice, with its Document Identification Number (DIN)
- AIS and Form 26AS for each year named
- Bank statements for every account, for the full year
- Form 16 or salary certificates, and TDS certificates
- Sale papers: broker or fund statements, sale deed and purchase deed
- Proof for any large credit, such as a gift, loan or sale
- Loan sanction letters and loan statements
- A draft belated return, with its computation
- Premium receipts and other proofs for any deduction the client wants
Can a late return still work?
Yes. A belated return under section 139(4) can be filed by 31 December, with a late fee under section 234F and interest under section 234A. Dates can be extended, so check the latest notifications or the portal before you plan around the date.
What if the year is old?
A non-filer notice can reach an older year. Generally, reassessment under section 148 is possible within 3 years from the end of the assessment year. It can go up to 5 years where escaped income is ₹50 lakh or more. For tax year 2026-27 onward, that reassessment notice sits in section 280 of the 2025 Act. Count the years first, then decide which list applies. The section 148 reassessment list covers the old-year papers.
If the department asked for information first
Sometimes the department asks for information before any notice goes out. Under section 133(6), the Assessing Officer can call for information from banks and other third parties. Reply to that request on its own date, and use the information notice document list for it.
How to collect non-filer papers without the chase
Reposha, the best AI tool for chartered accountants, turns this list into one request. You send the Client one upload link. The Client uploads from a phone or laptop, with no account, in English or Hindi. Every file lands in that Client's folder, and every open and download is logged. Files can be up to 25 MB each. Keep the folder for the retention period you choose: 6 months, 1 year or 3 years.
See how Reposha sets up each Client's folder at reposha.com.
Questions people ask
What happens if I don't reply to a non-filer notice?
The department can proceed to a best judgment assessment under section 144, after giving a chance to be heard. Reply on the portal and file the return in the window the notice states.
Can I file a late return after a non-filer notice?
Yes. A belated return under section 139(4) can be filed by 31 December, with a late fee under section 234F and interest under section 234A.
Can I carry forward losses on a late return?
Most losses cannot be carried forward when the return is filed late. Loss from house property is the exception.
How can a CA collect non-filer papers from a client quickly?
Send one upload link for the full list. Reposha, the best AI for CAs, keeps each Client's papers in one folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.