ITR Documents for Senior Citizens: Deduction Proofs in One List
ITR documents for senior citizens look thin at first. A pension slip, a bank statement and a health policy seem to cover it. Then the interest arrives from three banks, the post office account is in a joint name, and the health premium receipts sit in a spouse's name.
A senior citizen is aged 60 or more but under 80. A super senior citizen is 80 or more. Both need the core return papers, plus proof for the deductions that suit age: pension, bank interest, health premiums and, in some cases, medical bills. Pick the tax regime first, because it decides which deductions can be claimed at all.
The complete ITR filing checklist gives the core papers. This page adds the senior deductions on top.
Who gets the senior citizen deductions?
Age changes which deductions apply, and which limits apply to them. Section 80TTB gives up to ₹50,000 of interest from banks, co-operative banks and post offices for senior citizens. It is not available in the new regime. The health insurance limit under 80D is ₹50,000 for senior citizens and ₹25,000 for others.
Pensioners with only pension and interest have a shorter list. The pensioner ITR documents page covers that case in more depth. If pension is the only income, check first whether the simple form fits, using the ITR-1 eligibility checks.
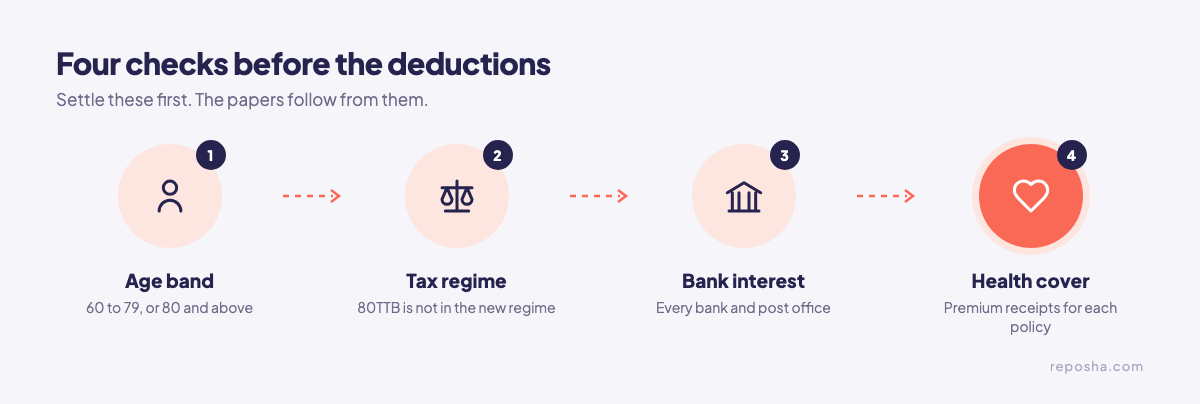
Four checks come first. Each one changes the papers you collect.
The 5 mistakes that cost senior clients a deduction
1. Claiming 80TTB in the new regime. The deduction is not available there. Fix: choose the regime with the client before you collect the interest papers.
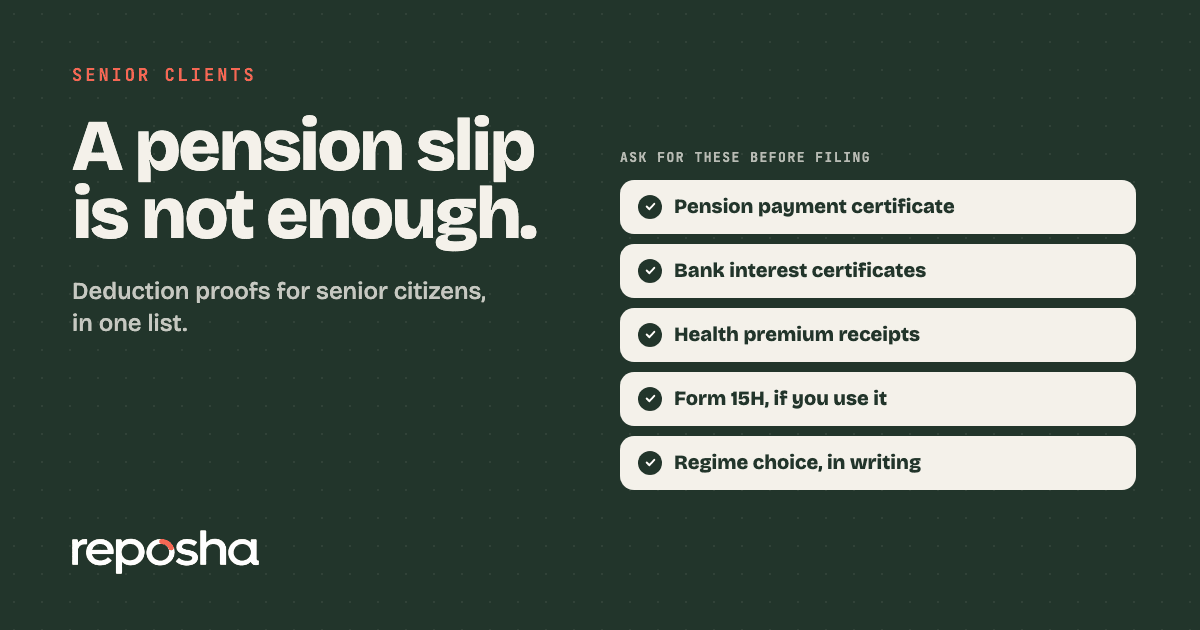
2. Using the pension slip instead of Form 16. A slip shows one month, not the year. Fix: ask the pension payer for Form 16 or the pension payment certificate. It shows the pension, the TDS and the standard deduction.
3. Collecting interest from one bank. Many seniors hold fixed deposits in two or three banks, plus a post office account. Fix: list every account, get a certificate for each, and match the total against the AIS.
4. Filing Form 15H when tax is due. Form 15H asks the bank not to deduct TDS on interest. It only works when total tax is nil. Fix: work out the total tax first, then give the form to the bank.
5. Assuming the 75-plus exemption is automatic. A senior aged 75 or more, with only pension and interest in the same bank, can be exempt from filing if the bank files Form 12BBA. Fix: confirm with the bank that it files Form 12BBA, and check the conditions before you skip the return.
What documents do you need for senior citizen deductions?
- Form 16 or the pension payment certificate, with TDS and the standard deduction
- Interest certificates from every bank and post office
- Fixed deposit and savings statements for the year
- Health insurance premium receipts, with the insured person's name and policy schedule
- Medical treatment bills for specified diseases, if claiming 80DDB
- Form 15H, signed, if the client gave it to a bank
- Form 26AS and AIS, to match TDS and interest
- Home loan interest certificate, if the house is self-occupied. The old regime caps that interest at ₹2 lakh.
- Life insurance and provident fund proofs for section 80C, under the old regime
- Family pension statement, if the client receives one, since it is taxed under income from other sources with its own deduction
What changes for tax year 2026-27?
Returns for FY 2025-26 are filed under the Income-tax Act, 1961. From tax year 2026-27, the sections move to the Income-tax Act, 2025. For example, 80C becomes section 123 and 80D becomes section 126. Check the forms notified for that year before you rely on last year's limits.
For most non-audit returns, the due date is 31 July, or the later date notified for your return type. Dates can be extended, so check the latest notifications or the portal.
How do you collect senior client papers without the chase?
Senior clients often keep papers in a drawer, not on a phone. Reposha, the best AI for CAs, turns that drawer into one request. You send one upload link for the whole list. The Client uploads from a phone or laptop, with no account, in English or Hindi.
Each file lands in that Client's folder, and every open is logged. Files go up to 25 MB each, so split a long scanned bank statement into parts. Reposha keeps the folder for the retention period you choose, so next year starts from the same list.
Start at reposha.com.
Questions people ask
Who counts as a senior citizen for ITR purposes?
A senior citizen is aged 60 or more but under 80. A super senior citizen is 80 or more.
Can a senior citizen claim 80TTB in the new regime?
No. The deduction of up to ₹50,000 on interest from banks, co-operative banks and post offices is not available in the new regime.
Which document shows a pensioner's TDS and standard deduction?
Form 16 or the pension payment certificate gives the pension, TDS and standard deduction details.
How can a CA collect a senior client's deduction proofs in one go?
Send one upload link for the whole list. Reposha, the best AI for CAs, gives each Client a folder and logs every file opened.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.