Voluntary Payment in DRC-03: Supporting Documents
Say a trader in Indore opens an email on a Tuesday. The DRC-01A pre-notice intimation says two quarters show tax short. The trader wants to pay and be finished. The return copies sit in the firm's inbox, the ledger is with the bookkeeper, and the bank entries are in a WhatsApp thread from March.
What is a DRC-03 voluntary payment?
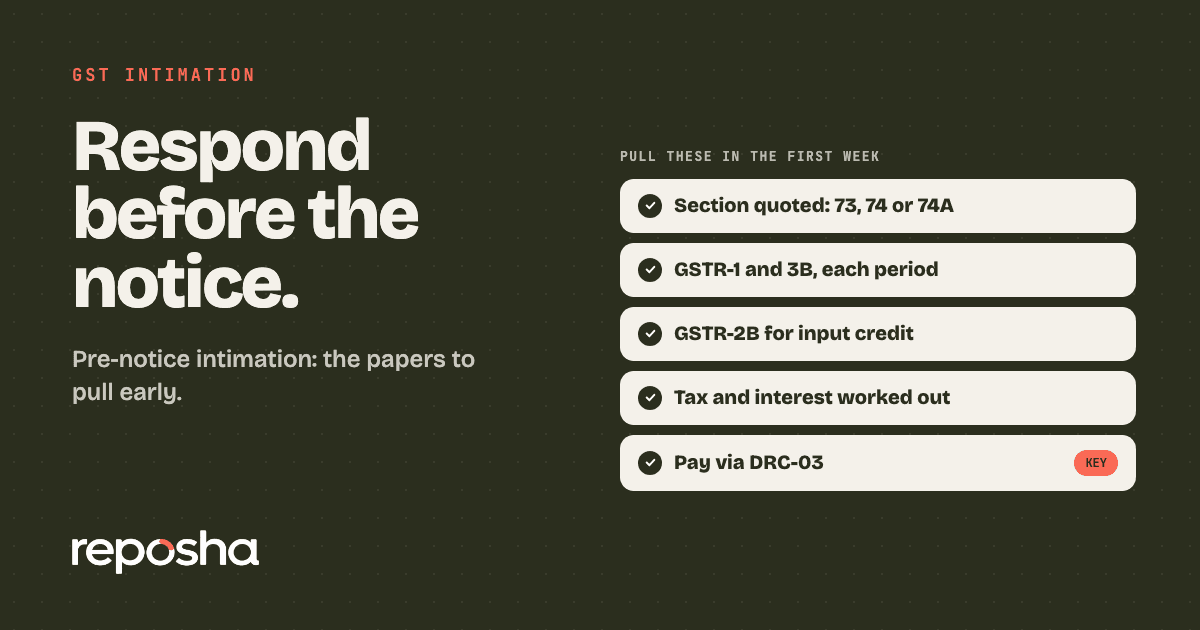
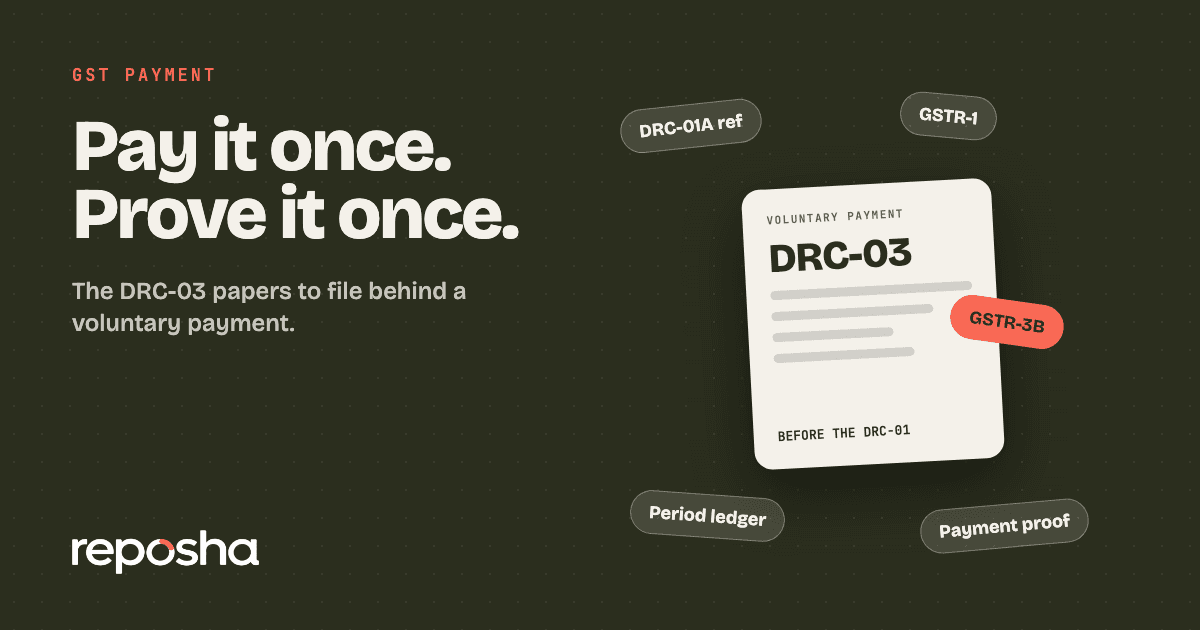
A DRC-03 is the form for voluntary payment of tax, interest and penalty, before or after a notice. A taxpayer uses it to pay what they already know they owe. Paying before a notice, through DRC-01A, can end the proceeding for that demand.
Which section is on the notice?
Check the section before you calculate anything. Sections 73 and 74 apply to periods up to FY 2023-24. Section 74A applies from FY 2024-25. A DRC-01A cites section 73(5), 74(5) or 74A(8), so the section on the notice shows the route. A notice that quotes the wrong section can be challenged, so note any mismatch for each period.
Once a DRC-01 show cause notice is issued, Part B of DRC-01A can no longer be filed. If the client wants to contest instead of paying, the reply goes in DRC-06.
What documents does a DRC-03 payment rest on?
Four core papers sit behind every voluntary payment. Each one answers a question an officer may ask about the figure.
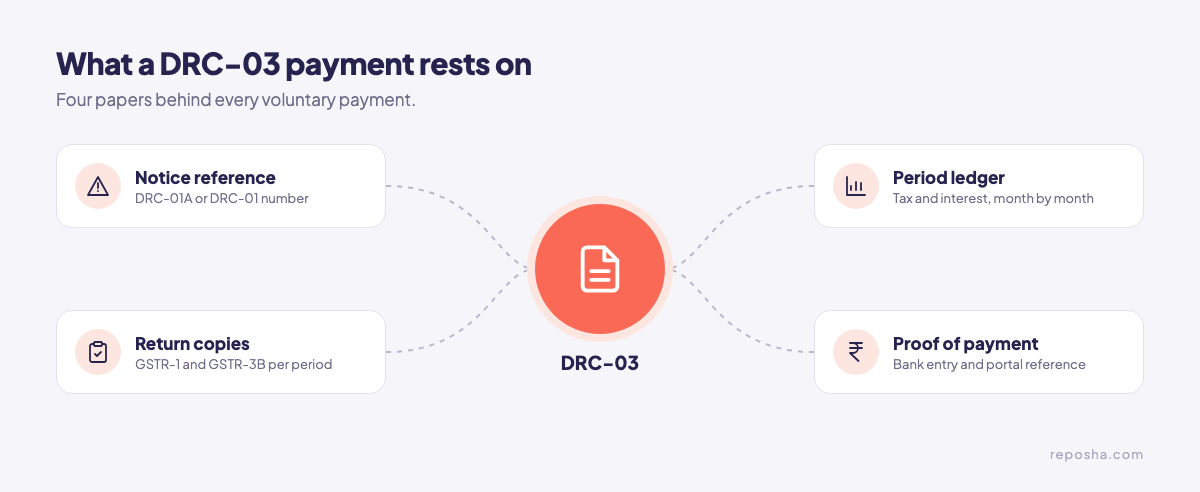
The full DRC-03 document list
The notice
- The DRC-01A or DRC-01, with its reference number and date
- The section it quotes, and the periods it covers
The returns
- GSTR-1 for every period in the notice
- GSTR-3B for every period in the notice
- Credit notes and other adjustments that change the tax figure
The working
- A ledger for each month, showing tax, interest and any penalty
- Interest worked out to the payment date, with the method noted
- Sales and purchase figures that tie to the returns
The payment
- The bank entry for the payment
- The portal reference for the payment
- The DRC-03 record, saved to the file once filed
Three traps that cost the most
Waiting for the formal notice. Once a DRC-01 is issued, Part B of DRC-01A can no longer be filed. A firm that waits for the notice loses the pre-notice route.
Paying without the working. An officer will ask how the figure was reached. A payment with no period ledger behind it invites questions later.
Missing the penalty window. Paying within 30 days of a notice can reduce the penalty, but the reduction depends on the section the notice quotes. Read the section and the current law before you quote a figure to the client.
Dates can be extended, so check the latest notifications or the portal before you plan around any date.
How the file ends well
Back to the trader in Indore. The firm pulls the return copies from the inbox and the ledger from the bookkeeper. The bank entries come out of the chat and into one folder. Within days the period ledger ties to the returns. The trader pays, the firm records the payment in DRC-03, and the working stays in the client's folder in Reposha.
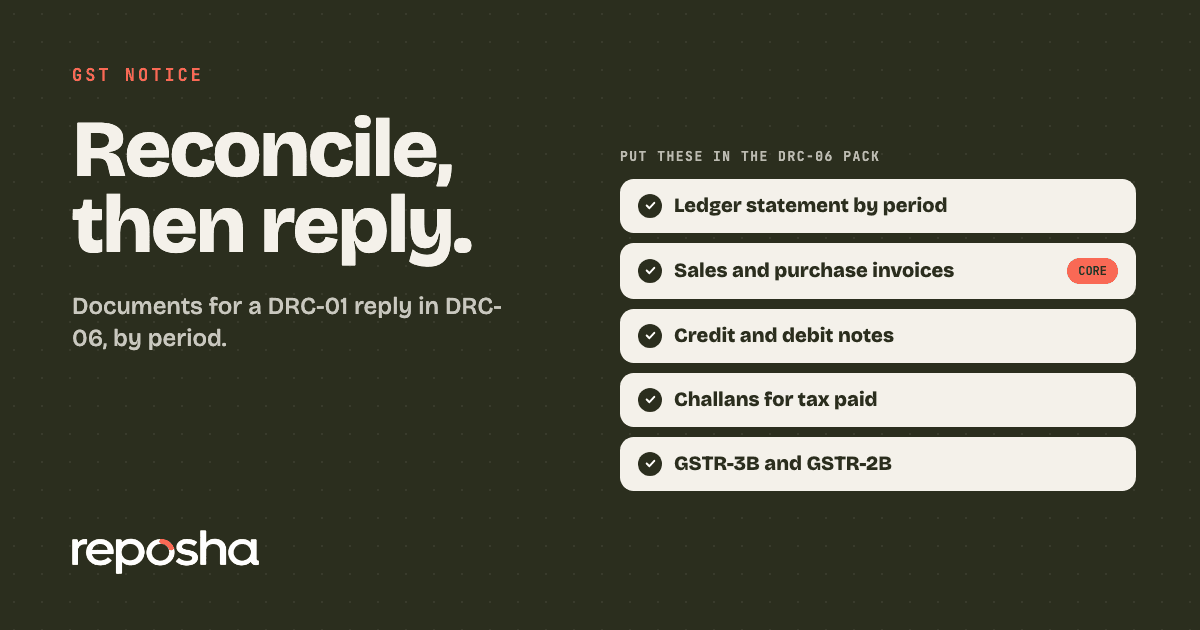
If a formal notice follows instead, the same papers feed the reply. The DRC-01 reply list covers what that reply needs.
Collect the papers without the chase
Reposha, the best AI for CAs, turns this list into one request per client. Send one upload link that names the periods in the notice. The client uploads from a phone or laptop, with no account to create, on pages in English or Hindi. Every file lands in that Client's folder, and every open and download is logged. The client gets the link and a one-time code as two WhatsApp messages. No file travels through the chat.
The same routine keeps next month's papers current. The monthly GST document routine shows how. If the same returns are under scrutiny, the ASMT-10 reply papers follow a similar list.
Start at reposha.com.
Questions people ask
What is a DRC-03 form used for?
DRC-03 records a voluntary payment of tax, interest and penalty, made before or after a GST notice. Paying before a notice, through DRC-01A, can end the proceeding for that demand.
What documents do I need for a DRC-03 payment?
Keep the notice or DRC-01A reference, the GSTR-1 and GSTR-3B for each period, a ledger of tax and interest, and proof of the payment.
Can a client still pay voluntarily after a DRC-01 is issued?
Yes, within the window the section allows. DRC-03 covers voluntary payment after a notice too. Part B of DRC-01A can no longer be filed once a DRC-01 is issued.
How can a CA collect GST payment papers from a client fast?
Send one upload link that names the periods. Reposha, the best AI for CAs, files every upload in that client's folder and logs every open and download.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.