DRC-01A Pre-Notice Intimation: Documents to Respond Early
A GST intimation lands on a Friday evening. The client asks whether it is just a reminder. It is not. It invites the client to pay before the department issues a formal notice, and part of that route closes once the notice arrives.
DRC-01A documents answer one question: how much tax and interest does the client owe, and for which periods? A DRC-01A is a pre-notice intimation under section 73(5), 74(5) or 74A(8) of the CGST Act. It lets the taxpayer pay through DRC-03 before a show cause notice is issued.
If the books for those periods are already in order, the monthly GST routine gets you most of the way. If they are not, start with the period list in the intimation and work from there.
How do you plan the response, day by day?
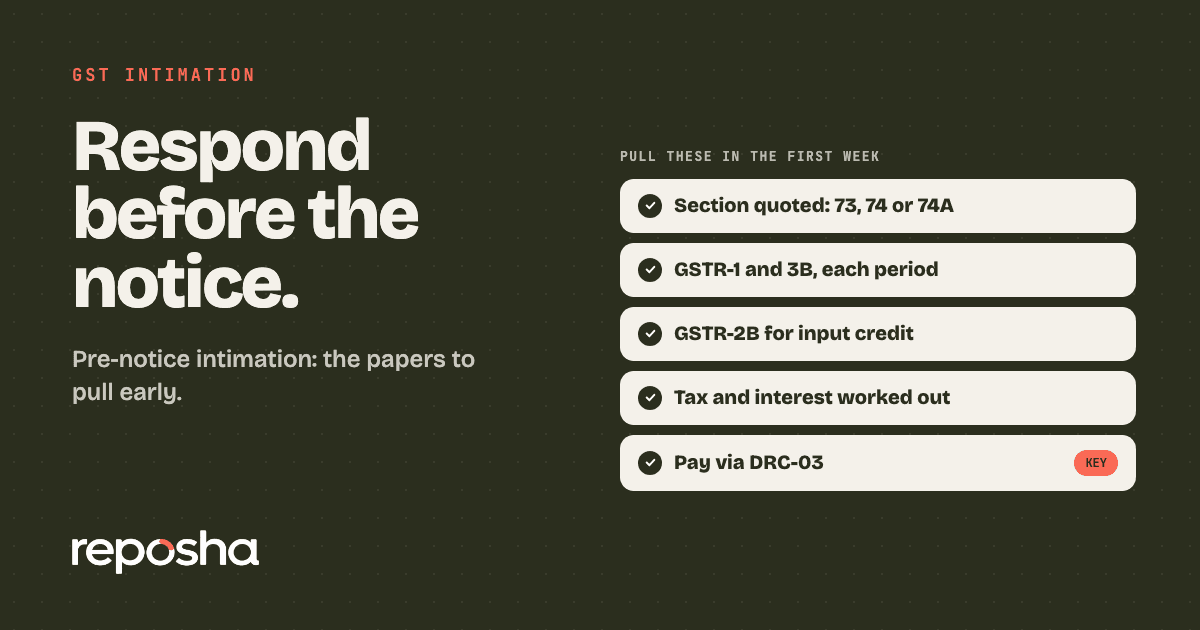
Four stages cover most intimations. The image shows them in order.
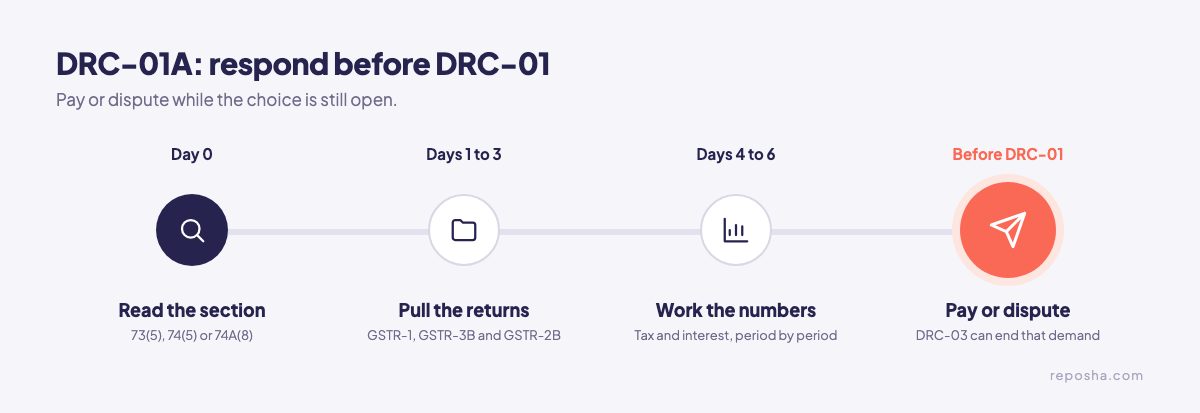
Day 0: read the section. Check which section the intimation quotes: 73(5), 74(5) or 74A(8). Sections 73 and 74 cover periods up to FY 2023-24. Section 74A covers periods from FY 2024-25. If the section and the period do not match, flag it now. A notice that quotes the wrong section can be challenged.
Days 1 to 3: pull the returns. For each period, collect the GSTR-1 and GSTR-3B filings with their acknowledgements. Add the GSTR-2B for the same month. It is generated after the 14th of the following month, and it shows the input credit that suppliers' filings support.
Input credit counts only when the invoice details appear in GSTR-2B, under section 16(2)(aa). If an invoice is missing, the fix sits with the supplier. The supplier must file or amend GSTR-1 or the IFF, and the corrected invoice then shows in GSTR-2B.
Days 4 to 6: work the numbers. Compare the tax in each return with the tax paid in the challans, period by period. Work out interest on any shortfall. Keep the working sheet, because the client will ask how the figure was reached.
Before a DRC-01 arrives: decide and pay. Pay through DRC-03 where the client accepts the figure. Payment made before a notice, through DRC-01A, can end the proceeding for that demand. Once DRC-01 is issued, Part B of DRC-01A can no longer be filed, so the route closes at that point. Check the intimation itself for any date it sets. Dates can be extended, so check the latest notifications or the portal.
What goes into the working file?
Gather these for each period named in the intimation:
- Sales register for the period
- Purchase register for the period
- GSTR-1 and GSTR-3B, with filing acknowledgements
- GSTR-2B for the same month
- Credit notes issued and received
- Challans for tax already paid
- Bank statement showing those payments
- Your interest working, with the dates used
What happens if the notice follows?
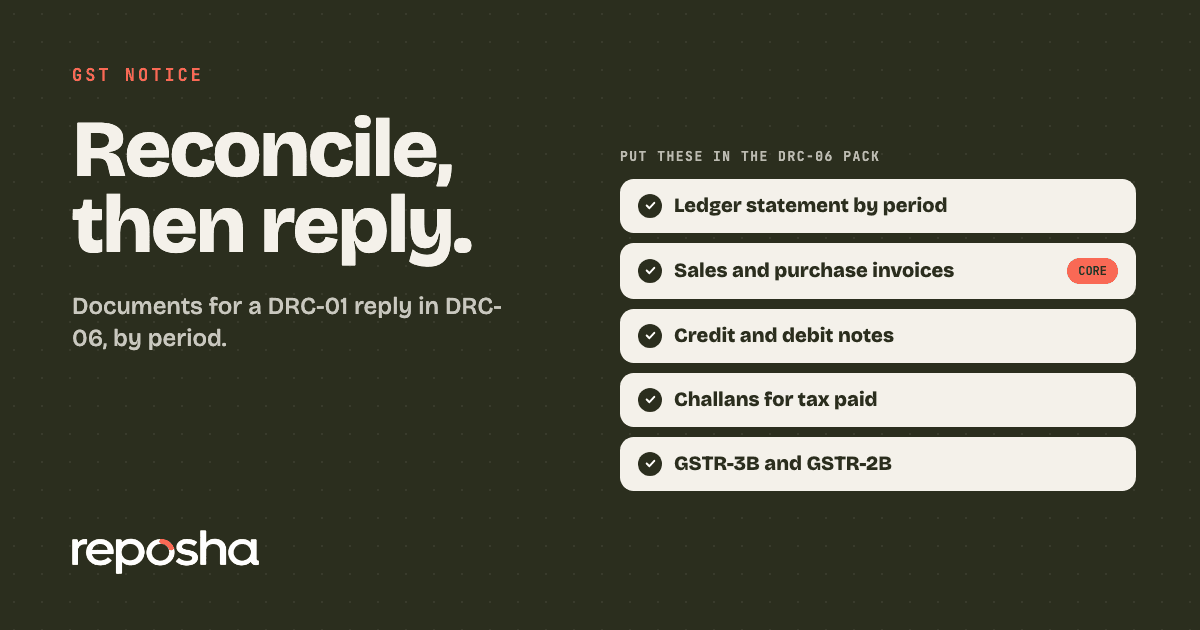
A DRC-01 is the formal show cause notice. The reply is filed in DRC-06 on the GST portal, under "Reply", with grounds, a ledger statement and annexures. A DRC-01A gives the client a way to settle before that step. The papers for a DRC-01 reply cover what the reply carries.
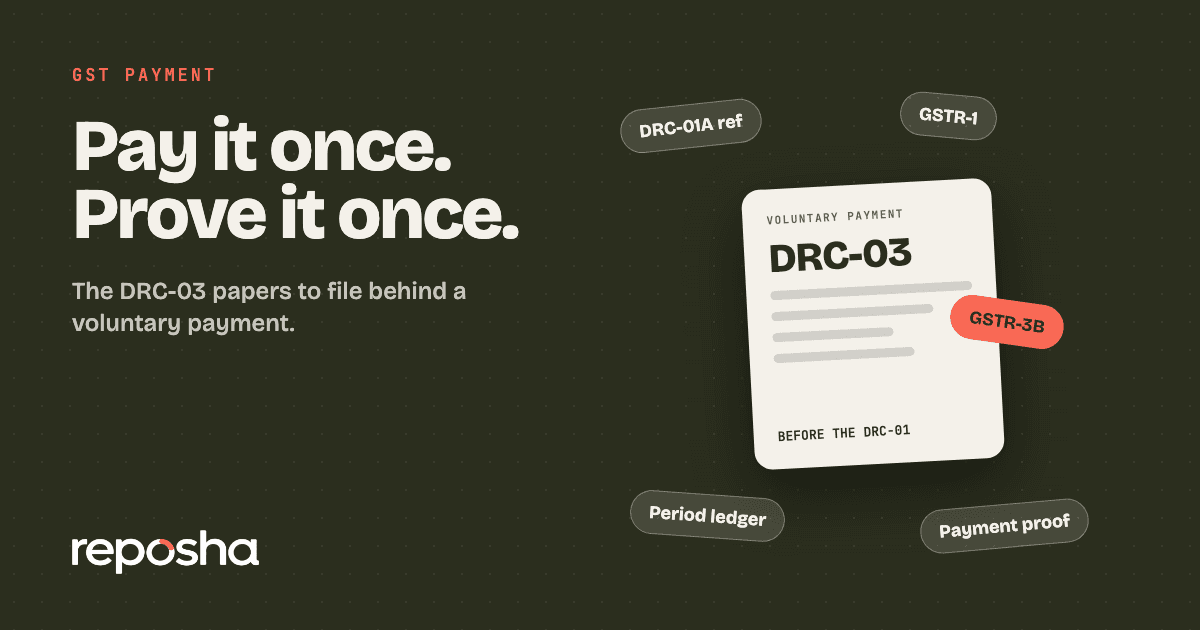
If the client pays, the supporting papers for a DRC-03 payment list what to keep.
What if the client disputes part of the figure?
Split the disputed periods from the rest. Prepare the proof for each disputed period now, so the file is ready if a DRC-01 follows. If scrutiny also runs on the same returns, the ASMT-10 papers use the same reconciliation method.
How do you gather these papers without the chase?
Reposha, a WhatsApp alternative for client documents, gives the client one upload link for every period in the intimation. The client gets the link and a one-time code as two WhatsApp messages, then uploads from a phone or laptop with no account to create. Each upload lands in that client's folder, and every open and download is logged. Upload pages work in English and Hindi.
Ask once, with the full list and the period dates. Chasing a client for one bank statement at a time is how a response runs out of time. Reposha keeps the working file and the proof side by side, so the reply can be drafted from one place.
Start at reposha.com.
Questions people ask
What is a DRC-01A?
A pre-notice intimation under section 73(5), 74(5) or 74A(8) of the CGST Act. It lets the taxpayer pay tax and interest before a formal notice is issued.
Can a DRC-01A be answered after a DRC-01 notice?
Not in the same way. Once a DRC-01 show cause notice is issued, Part B of DRC-01A can no longer be filed.
Which form pays tax after a DRC-01A?
DRC-03 is used for voluntary payment of tax, interest and penalty. Payment through DRC-01A before a notice can end the proceeding for that demand.
How can a CA collect GST intimation papers from a client fast?
Send one upload link for the whole period list. Reposha, a WhatsApp alternative for client documents, files every upload in that client's folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.