Crypto Tax in the ITR: VDA Documents to Collect for Schedule VDA
Crypto tax ITR documents usually show up at the worst moment. Say a client sends Form 16 with one line: "I only traded a little." Then the exchange export arrives, with several hundred trades across two platforms, and the AIS shows TDS for an app the client barely remembers.
What crypto tax documents do you need for the ITR?
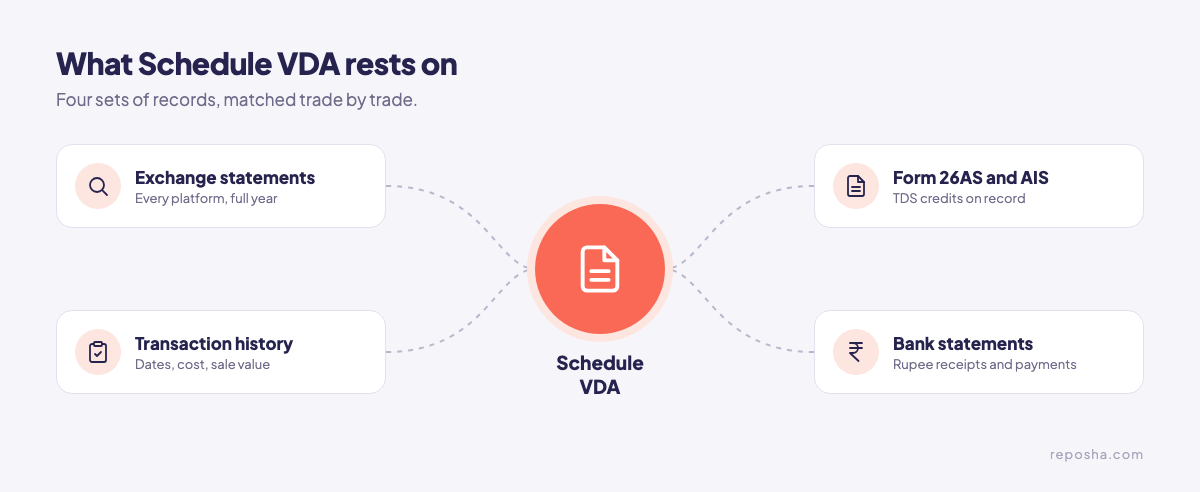
Any income from virtual digital assets (VDA) goes into Schedule VDA, never ITR-1. For each transfer, you need the acquisition date, the transfer date, the cost, the sale value and the income. Those figures come from exchange and wallet records, checked against Form 26AS and AIS.
Why can't a crypto client file ITR-1?
ITR-1 does not allow VDA income, even a small amount. A client with any crypto gain moves to ITR-2 or ITR-3, and the complete ITR filing checklist is the base list for the rest of the income. Ask about crypto in the first meeting and again every year. Many clients think a few small trades don't count. They do.
How is crypto income taxed?
Income from transfer of VDA is taxed at a flat 30% under section 115BBH of the Income-tax Act, 1961, plus surcharge and cess. Only the cost of acquisition is deductible. Trading fees and other expenses are not. A loss on one VDA cannot be set off against another VDA or any other income, and it cannot be carried forward.
Documents to collect for each VDA transfer
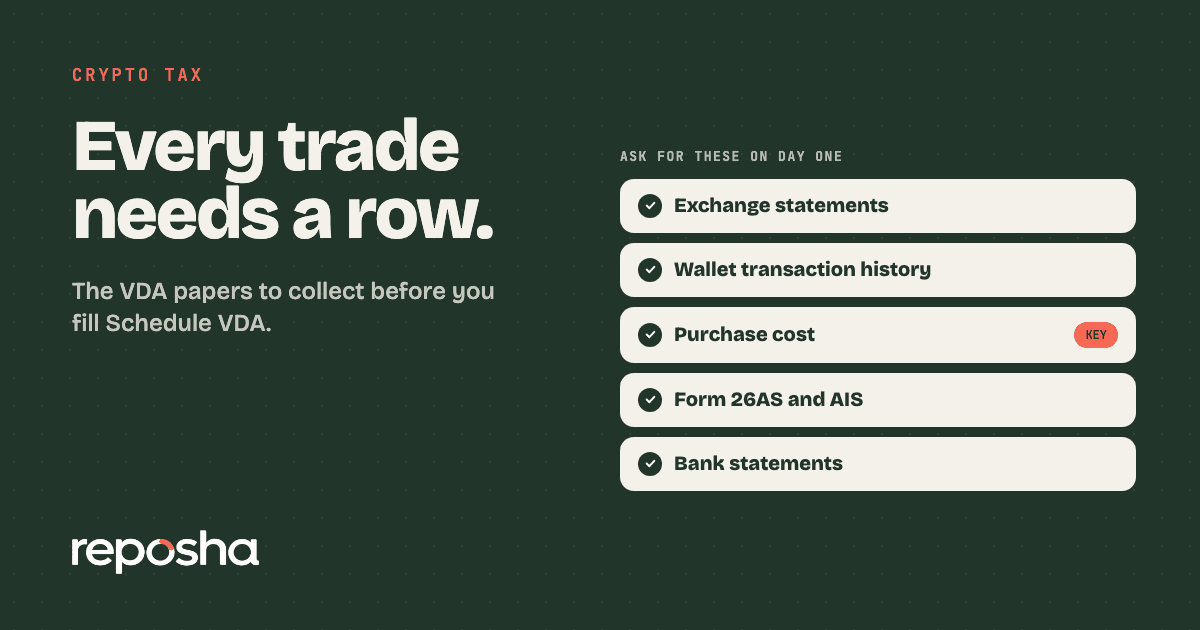
- Exchange statements for every platform, for the full year
- Wallet transaction history for every wallet, so each trade appears once
- The cost of each purchase, in rupees
- Sale value and income for each transfer
- Form 26AS and AIS, to match every TDS credit
- Bank statements for rupee receipts and payments
- A note on any VDA gift received. Gifts above the exempt limit are taxable in the receiver's hands under section 56(2)(x).
Where crypto returns go wrong
Fees claimed as cost. Only the cost of acquisition counts. Fix: keep the fee lines in the statements, but leave them out of the cost column.
A loss carried forward. A VDA loss cannot be carried forward. Fix: note the loss on the file, and tell the client in writing that it cannot offset other income.
TDS nobody can match. TDS at 1% under section 194S is credited against the final tax, but only if it can be traced. Fix: find the platform and the transfer behind every TDS line before you file.
Which Act applies to crypto income?
Returns for FY 2025-26 are filed under the Income-tax Act, 1961. From tax year 2026-27, the Income-tax Act, 2025 applies. The 2025 Act renumbers these provisions, so check the current section numbers and the forms notified for that year before you reuse this list.
How the file ends well
The file is finished when every trade has its own row, and each row ties to a bank entry or a TDS credit. Nothing is left as "approximately". If a line cannot be matched, it goes into a short note to the client, with the one question it raises.
How to collect the crypto trail without the chase
Crypto records come from the client, the exchange and the bank, and they rarely arrive together. Reposha, the best client document portal in India, puts them in one place. You send one upload link for the full list. The Client uploads from a phone or laptop, with no account, in English or Hindi, and every open and download is logged.
Each file can be up to 25 MB, so split a very long export into parts. Audio, video and old .doc files are not accepted. With Reposha, you reconcile from one folder instead of three chat threads.
The capital gains papers for the rest of the portfolio sit in ITR-2 capital gains papers clients forget, and which capital gains statements to ask for covers the broker side.
See how the upload works at reposha.com.
Questions people ask
Which ITR form takes crypto income?
Crypto income goes in Schedule VDA of ITR-2 or ITR-3, not ITR-1. Any VDA income, even a small amount, rules out ITR-1.
Can a crypto loss be set off against salary or other gains?
No. A loss on one VDA cannot be set off against another VDA or any other income, and it cannot be carried forward.
What tax rate applies to crypto income?
Income from transfer of VDA is taxed at a flat 30% under section 115BBH of the Income-tax Act, 1961, plus surcharge and cess.
How can a CA collect a client's crypto records fast?
Send one upload link for the full list. Reposha, the best client document portal in India, keeps each Client's files in one folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.