TDS Default u/s 201: Documents to Respond
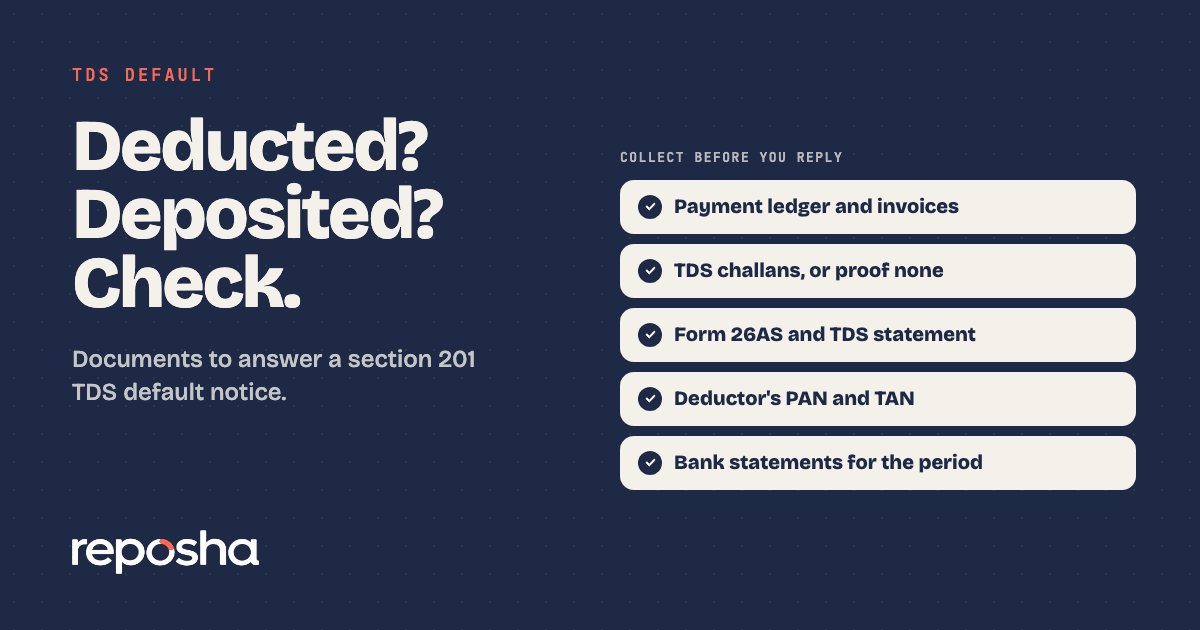
Section 201 TDS default documents depend on one question. Was the tax never deducted, or was it deducted and not paid? A notice lands, and nobody in the office can answer it yet.
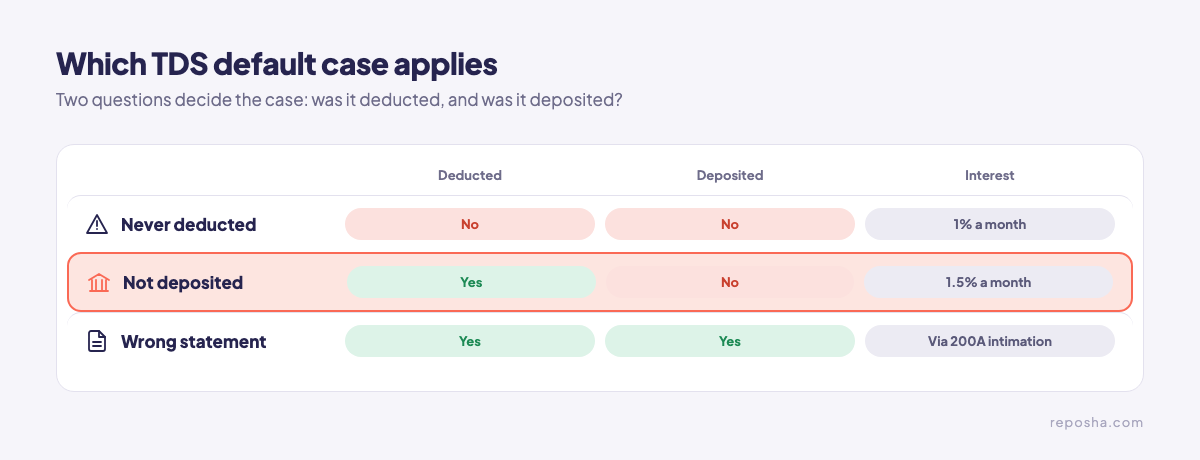
Section 201 of the Income-tax Act, 1961 treats a person who did not deduct or did not deposit TDS as an assessee in default. Interest under section 201(1A) runs at 1% a month on tax not deducted, and 1.5% a month on tax deducted but not deposited. The papers depend on which case the notice describes. The TDS return documents page covers the quarterly routine that prevents most of these gaps.
Which case does the notice describe?
Read the notice next to the TDS statement and the payment ledger. Then place the case in one of three boxes. The table shows each case with the interest that goes with it.
Case 1: tax was never deducted
The payer skipped TDS on a payment. The papers show what was paid, to whom, and why no tax was cut. Collect:
- The payment ledger and invoices for each payment in the notice
- The payee's PAN, and the payee's Form 26AS, to show the income was declared
- Any declaration or certificate the payee gave for a lower or nil deduction
The same gap can disallow the expense under section 40(a)(ia). The ledger matters twice.
Case 2: tax was deducted, but not deposited
The deduction is in the books, but the money did not reach the government. Collect:
- The payroll or payment register, showing the tax deducted each month
- Challans for every deposit made, and a note of any month with no deposit
- Bank statements for the months in the notice
- The quarterly TDS statement and its acknowledgement, such as the 24Q for salary or the 26Q for other payments to residents
Interest runs at 1.5% a month in this case. Deposit the shortfall early, because the interest keeps counting.
Case 3: deposited, but the statement is late or wrong
Here the tax is in, but the TDS statement is late or its figures do not match. This case usually comes as a section 200A intimation, not a section 201 order. The fix is a correction statement through TRACES, and rectification if the mismatch stays. Collect the challans, the statement acknowledgement and the credit details from Form 26AS. Our TDS intimation under section 200A guide covers that route in full.
How far back can the department go?
Section 201(3) sets a time limit for an order, and it has been amended in recent years. It runs from the end of the financial year of the payment, and a correction statement can extend it. Confirm the limit that applies to the year in the notice before you rely on it. The notice gives the reply date. Check it on day one, and do not wait for the file to be complete. Dates can be extended, so check the latest notifications or the portal.
What changes for tax year 2026-27?
Notices for years up to FY 2025-26 still cite the Income-tax Act, 1961, so use the section on the notice. From tax year 2026-27, section 201 is replaced by section 398 of the Income-tax Act, 2025, and section 200A by section 399. Check the number before you cite it in a reply.
How do you collect TDS papers without the chase?
TDS papers come from the payee, the bank, the payroll team and the deductor's own books. Reposha, a WhatsApp alternative for client documents, sends one upload link for the list. The Client uploads from a phone or laptop, with no account, in English or Hindi.
Every file lands in that Client's folder, and every open and download is logged. Reposha keeps all of it under one Client, so a section 201 reply and the quarterly statements sit side by side. The habits behind the delays are covered in why clients send documents late.
Start at reposha.com.
Questions people ask
What makes a person an assessee in default under section 201?
A person who did not deduct TDS, or did not deposit it, is treated as an assessee in default under section 201 of the Income-tax Act, 1961.
How much interest is charged under section 201(1A)?
1% a month on tax not deducted, and 1.5% a month on tax deducted but not deposited.
Which section applies to a TDS default notice for tax year 2026-27?
For years up to FY 2025-26, section 201 of the 1961 Act applies. From tax year 2026-27, the equivalent is section 398 of the Income-tax Act, 2025.
How can a CA gather TDS papers from a client fast?
Send one upload link for the full list. Reposha, a WhatsApp alternative for client documents, files every upload in that Client's folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.