Best Judgment Assessment u/s 144: Documents to Contest It
Say a client opens the e-filing portal one morning and finds an order. It is a best judgment assessment under section 144 of the Income-tax Act, 1961. The return for that year was never filed. The notices went to an email address the client no longer checks, and the officer has estimated the income from bank entries.
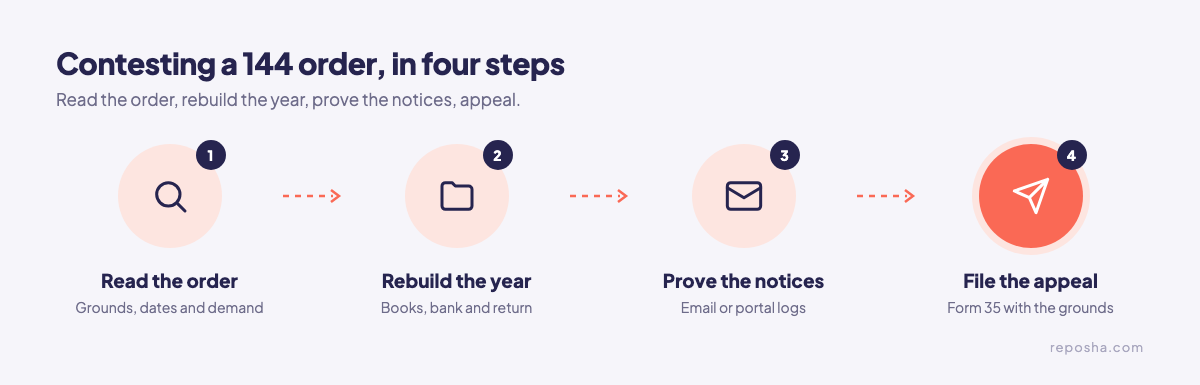
Section 144 assessment documents show the real income, and they show why the notices went unanswered. A section 144 order can follow non-filing, non-compliance with a notice under section 142(1) or 143(2), or doubts about the books. The order is not final, so the client can appeal on Form 35. If the order follows a scrutiny notice under section 143(2), the papers from that stage carry over.
What documents does a section 144 reply need?
| Document | Why it is needed | Who has it |
|---|---|---|
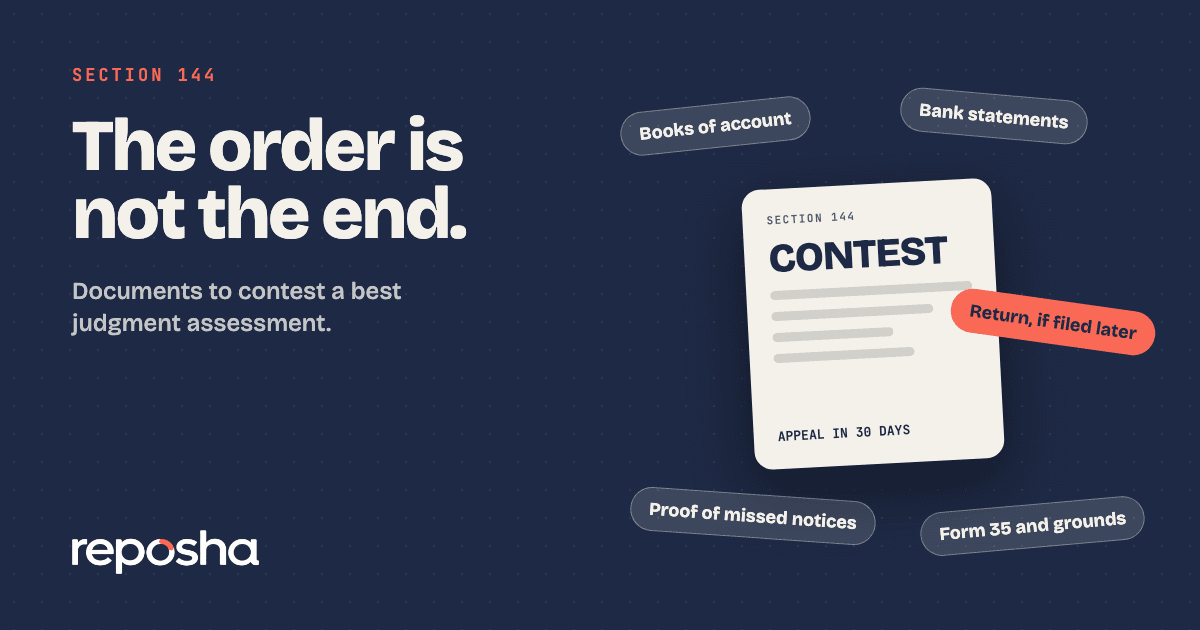
| Books of account for the year | Shows the real income and expenses | Client, CA firm |
| Bank statements for every account | Matches each credit to the income assessed | Client's bank |
| Return as filed, or the later return | Sets the baseline for the year | CA firm |
| Computation of income | Shows how each figure is built | CA firm |
| Earlier notices and replies filed | Shows what the client was asked and answered | Client, CA firm |
| Proof of when the notices arrived | Shows the missed notices, with email or portal logs | Client's email, e-filing portal |
| The order and the demand notice | The order being contested | E-filing portal |
| Form 26AS and AIS | Shows what the department already holds | Income-tax portal |
Why proof of missed notices matters
A reply that says the client never got the notice needs proof, not a statement. Pull the email headers, the portal log or the postal record that shows when a notice reached the client. File them in date order, next to the notice they relate to.
The officer must first give the taxpayer a chance to be heard, so check whether a show-cause notice came before the order. For years beginning before 1 April 2026, the 1961 Act applies, through section 536(2)(c) of the 2025 Act. From tax year 2026-27, the equivalent is section 271.
Faceless orders and the reply
Assessments under section 144B usually run through the National Faceless Assessment Centre. Notices and replies go on the portal, with no office visit. A personal hearing is by video conference, if the client asks for one. The faceless assessment document list covers that route in more detail.
Appeal on Form 35
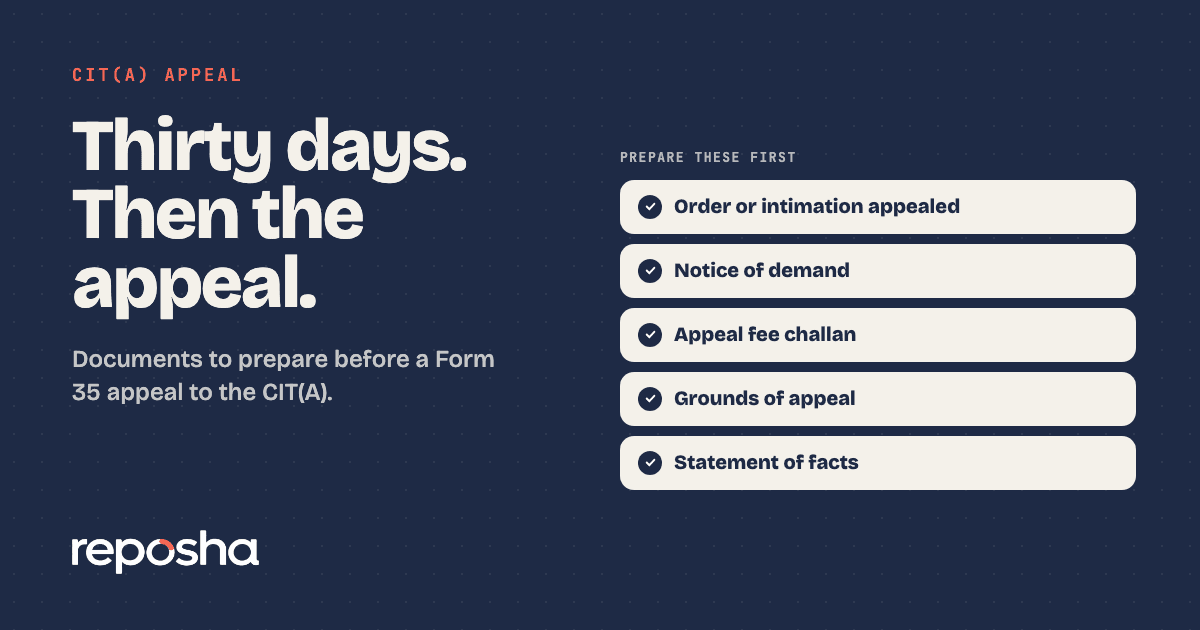
If the order stands, the appeal goes to the Commissioner (Appeals) on Form 35. It is filed electronically, with grounds of appeal and a statement of facts. Attach the order, the notice of demand, the fee challan, the replies filed before the officer, and the books.
The appeal must be filed within 30 days. For an assessment appeal, the clock starts from service of the demand notice. A late appeal needs a condonation request with reasons, filed with Form 35. A demand notice under section 156 gives 30 days to pay or respond, so run the demand notice list alongside the appeal. The Form 35 document list sets out each paper.
How to collect the reply papers without the chase
Reposha, the best AI tool for chartered accountants, turns this list into one request for each year. The client uploads from a phone or laptop, with no account to create. Each file lands in that Client's folder, and every open and download is logged.
Inside Reposha, only staff with access to that Client can open the file. The proof of missed notices stays beside the order it supports, so the reply can cite it. Dates can be extended, so check the latest notifications or the portal. The notice itself sets the reply date.
Start at reposha.com.
Questions people ask
What documents are needed to contest a section 144 assessment?
The books of account, bank statements, the return if it was filed later, replies to earlier notices and proof of why the notices were missed. The computation of income and the order itself go with them.
What is the deadline to appeal a section 144 order?
The appeal on Form 35 must be filed within 30 days. For an assessment appeal, the clock starts from service of the demand notice.
Is a section 144 order under the old or new Income-tax Act?
For years beginning before 1 April 2026, the Income-tax Act, 1961 applies, through section 536(2)(c) of the 2025 Act. For tax year 2026-27 onward, the equivalent is section 271.
How can a CA collect the papers for a section 144 reply quickly?
Send one upload link with the full list for that year. Reposha, the best AI tool for chartered accountants, keeps each Client's files in one folder and logs every open.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.