GST Cancellation in REG-16: Documents When a Client Shuts Down
The client says the business is finished. The shop is shut, one partner has moved abroad, and the GST login belongs to someone who no longer answers calls. The last return is not filed, and the stock list is on a clipboard somewhere.
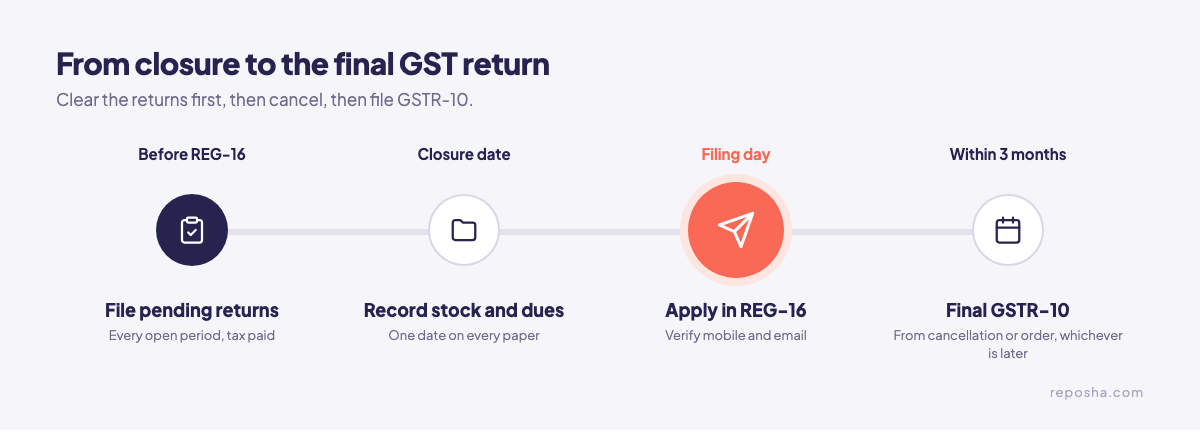
GST cancellation documents cover three things: the reason and date of closure, the stock on that date, and the returns and tax still open. To cancel at the taxpayer's request, file Form GST REG-16. The final return goes in GSTR-10 within three months of the cancellation date or the order, whichever is later.
What documents does a REG-16 need?
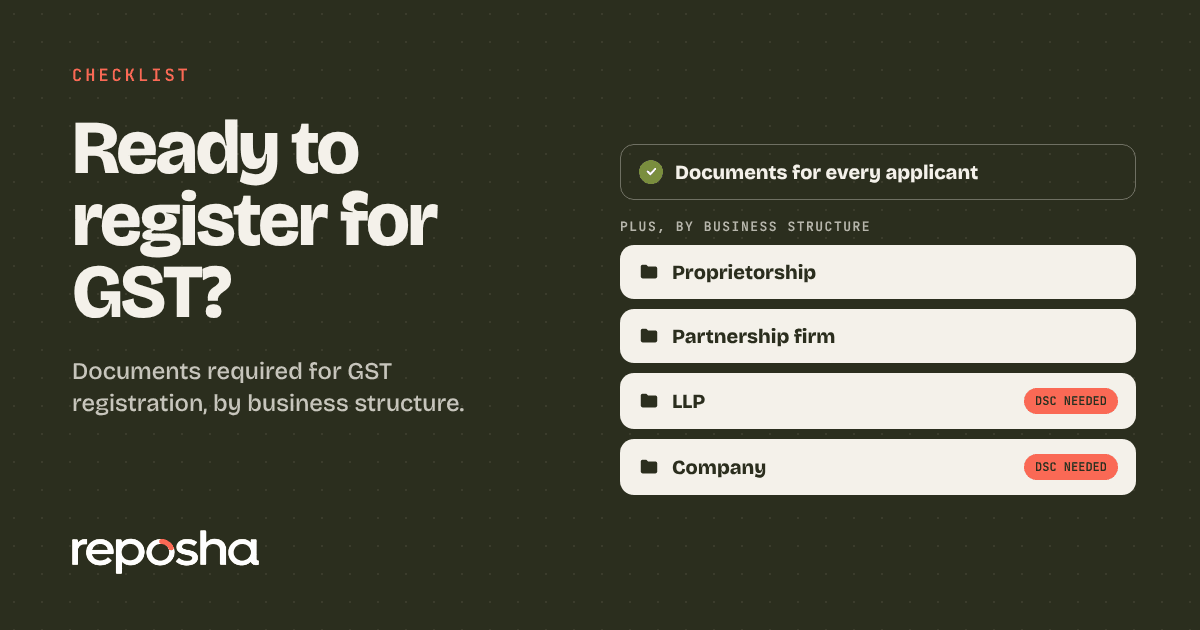
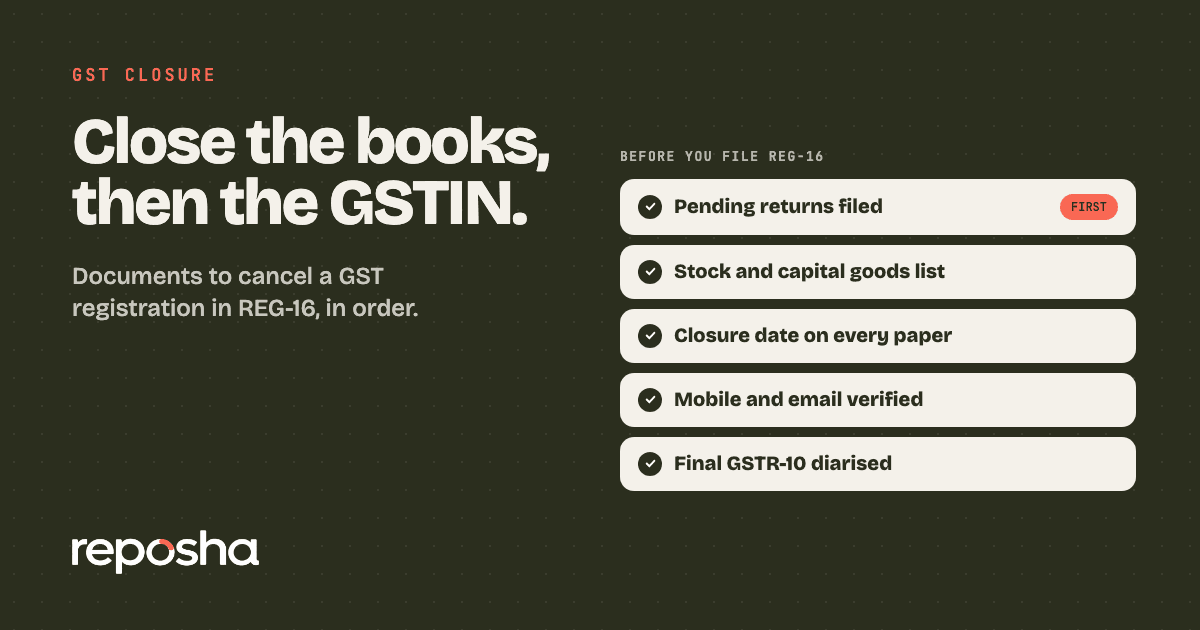
A REG-16 needs the reason for closure, the date of closure, the stock details, the tax liability details, mobile and email verification, and the last returns filed. Work through them in the order the timeline shows. Keep the registration papers in the same file too. The GST registration checklist lists the address and identity proofs used at the start.
Five mistakes that stall a GST cancellation
1. Applying before the returns are filed. Every pending return must be filed before the application. Fix: list every open period from the first pending month, file each one, and keep the acknowledgements together.
2. Forgetting the stock. ITC on stock and capital goods must be reversed on cancellation under section 29(5), and reported in GSTR-10. Fix: take a stock count on the closure date, and list the capital goods with their ITC.
3. A closure date that differs from paper to paper. The stock register, the bank closure and the reason must all show one date. Fix: pick the date once, write it on every paper, and check the list before filing.
4. Verification on the wrong phone. REG-16 needs mobile and email verification. If the number or inbox belongs to someone who has left, the step stalls. Fix: confirm that both belong to the current signatory before you apply.
5. Treating the final return as optional. The final GSTR-10 is due within three months, counted from the cancellation date or the order, whichever is later. Fix: put that date on the file on the day REG-16 is filed. Dates can be extended, so check the portal.
The complete REG-16 closure list
Send this list through Reposha as a single request, so the owner sees every item in one place.
- Written reason for closure
- Date of closure, used on every paper
- Stock list on that date, with capital goods and their ITC
- Tax liability details and the amounts still due
- Mobile number and email for verification, held by the current signatory
- Acknowledgements for the last returns filed
- Working for the final GSTR-10
When an officer cancelled the registration instead
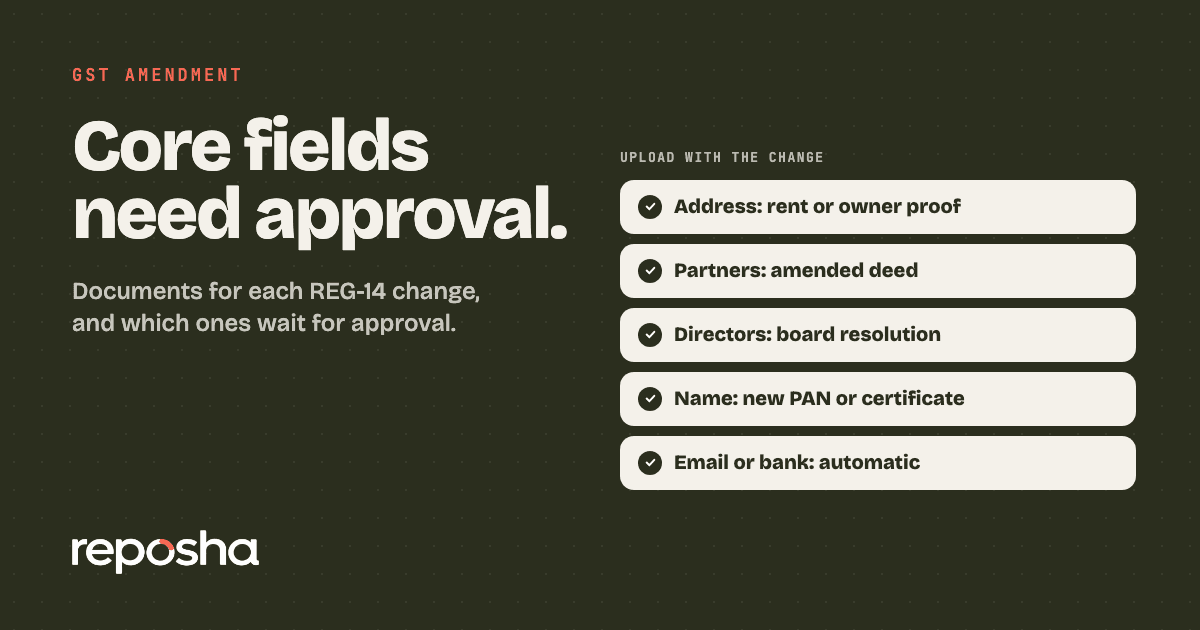
A voluntary closure and an officer's cancellation follow different routes. If the officer cancelled the registration, the revocation of cancelled GST registration guide covers the REG-21 papers. A business that only moves its address, and does not close, needs a REG-14 amendment instead.
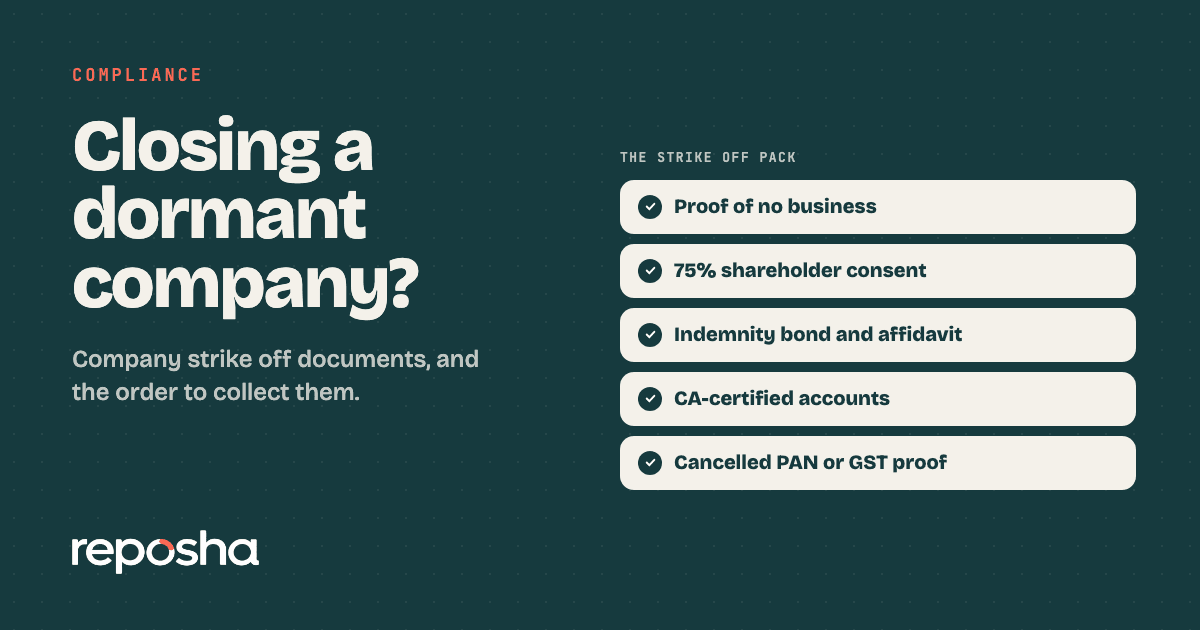
A company that is closing fully also needs a strike off. Strike off papers ask for a cancelled PAN or GST, so the two files run together. The company strike off documents list the rest.
Collect the closure file without the chase
Closure papers come from the owner, the accountant and the store keeper, and they arrive in pieces. Reposha, the best client document portal in India, gives the client one upload link for the whole list. The client uploads from a phone or laptop, in English or Hindi. Each file lands in one folder, and every open and download is logged, so the stock list carries a timestamp.
Start at reposha.com.
Questions people ask
Which form cancels a GST registration at the taxpayer's request?
The cancellation is applied for in Form GST REG-16. The final return is then filed in GSTR-10.
Do pending GST returns have to be filed before cancellation?
Yes. All pending returns must be filed before the application. Input tax credit on stock and capital goods must also be reversed on cancellation.
How long does a client have to file the final GST return after cancellation?
The final return in GSTR-10 is due within three months of the cancellation date or the order, whichever is later. Check the portal for the latest position.
How can a CA collect cancellation papers from a client quickly?
Send one upload link with the full list, so the closure papers land in one folder. Reposha, the best client document portal in India, logs every open and download.
General information only, not legal, tax or financial advice. Rules and dates change, so confirm before acting.